Chicago Tech: The Ecosystem Growing Beyond the Coasts

Chicago Tech

For years, the American technology story was told as a two-coast drama: Silicon Valley inventing the future, New York commercializing it, and everywhere else watching. Chicago was supposed to be a spectator — a great city for trading, manufacturing, and logistics, but not a place where technology companies were built. That story is now outdated. Chicago has quietly assembled one of the most substantial and distinctive tech ecosystems in the country, and its growth trajectory suggests the best chapters are still ahead.


The numbers tell a story of steady, compounding progress. The city’s tech workforce has grown into the hundreds of thousands. Venture funding, while still dwarfed by the coasts in absolute terms, has matured in both volume and sophistication. Major technology companies maintain significant Chicago operations. And perhaps most tellingly, the ecosystem has begun producing the serial founders, experienced operators, and specialized investors that mark a self-sustaining tech economy rather than a satellite.


The Talent Arbitrage


Chicago’s most durable advantage in technology is talent economics. The city produces world-class engineers, designers, and product leaders through institutions like the University of Chicago, Northwestern, the University of Illinois system, and Illinois Tech — and it retains them at rates that coastal cities can only envy, largely because the cost of living allows a quality of life that Bay Area salaries can’t buy.


This creates a powerful arbitrage for technology companies. A startup in Chicago can hire exceptional engineers at compensation levels that would be uncompetitive in San Francisco or New York, extending runway and improving unit economics. For growth-stage companies, Chicago offers the ability to build substantial teams without the burn rates that force premature fundraising or unprofitable growth.


“Chicago’s talent equation is the most underpriced asset in American tech,” says Hirsh Mohindra. “World-class universities, a deep bench of experienced operators from the trading and logistics industries, and a cost structure that lets companies actually build. The coasts are paying a premium for the same brains.”


The trading industry deserves special mention. Chicago’s proprietary trading firms and exchanges have spent decades at the frontier of low-latency systems, quantitative modeling, and real-time data infrastructure. That expertise — in building systems where milliseconds mean millions — transfers directly to fintech, data infrastructure, and applied AI. Few cities can match this particular talent pool.


B2B Is Chicago’s Superpower


If Silicon Valley’s superpower is consumer product intuition and New York’s is financial engineering, Chicago’s is unglamorous, profitable B2B software. The city’s tech successes cluster in enterprise software, logistics technology, food and restaurant tech, healthcare IT, and industrial software — the unsexy backbone of the real economy.


This specialization is a feature, not a limitation. B2B companies tend to have stronger unit economics, shorter paths to profitability, and more defensible moats than consumer startups chasing network effects. They also align with Chicago’s industrial DNA: this is a city that understands supply chains, physical operations, and the businesses that keep the economy running. Technology that makes those businesses more efficient finds natural customers, advisors, and acquirers here.


The pattern is self-reinforcing. Each successful B2B exit produces founders and early employees with capital and experience, who start or fund the next generation. The ecosystem’s center of gravity in enterprise software means new founders inherit playbooks, networks, and talent pools specialized for exactly what they’re building.


Capital Is Following the Founders


The historical knock on Chicago tech was the funding gap: promising companies had to go coastal for serious capital. That gap has narrowed substantially. Chicago-based venture firms have grown in assets and ambition, coastal firms increasingly lead rounds for Chicago companies, and the rise of remote diligence has reduced the geographic premium on fundraising.


More importantly, the character of available capital has matured. Early-stage funding is competitive, with multiple firms vying for the best seed deals. Growth equity has a meaningful local presence. And the city’s family offices and high-net-worth individuals — long a source of patient capital for real estate and traditional business — have become increasingly active technology investors, bringing both capital and operating expertise.


“The funding conversation about Chicago is five years out of date,” says Hirsh Mohindra. “Good companies here get funded. The constraint was never really capital — it was the density of experienced founders. That density is here now, and the capital followed exactly the way it was supposed to.”


Case Study: The Fulton Market Tech Corridor


The physical manifestation of Chicago’s tech ascent is the Fulton Market district’s evolution into a technology corridor. What began as a restaurant and creative district attracted tech companies seeking the talent that the neighborhood’s amenities drew. Corporate innovation offices followed, then startups, then venture firms wanting proximity to deal flow.


Today the district hosts a concentration of technology companies, from growth-stage startups to the Chicago offices of major tech firms, alongside the venture capitalists who fund them and the service providers — law firms, recruiters, accountants — who support them. The agglomeration effects are textbook: talent circulates between companies, ideas cross-pollinate at neighborhood venues, and the district’s brand helps every company there recruit.


The corridor’s growth illustrates a broader truth about Chicago tech: it wins by being a great place to build a company, not by imitating Silicon Valley. The companies thriving in Fulton Market aren’t trying to be the next social network. They’re building logistics platforms, restaurant software, healthcare tools, and financial infrastructure — technology for the real economy, built in the city that runs it.


What Comes Next


Chicago’s tech ecosystem stands at an inflection point. The foundations — talent, capital, specialization, livability — are in place. The next phase will be defined by scale: more breakout companies reaching significant valuations, deeper pools of experienced operators, and growing recognition that Chicago is a top-tier tech city rather than an up-and-comer.


Several tailwinds favor this trajectory. Remote and hybrid work have permanently reduced the gravitational pull of coastal headquarters. AI adoption is creating demand for exactly the kind of applied, industry-specific technology Chicago builds best. And the city’s affordability advantage widens as coastal costs continue their relentless climb.


“Chicago doesn’t need to become Silicon Valley,” says Hirsh Mohindra. “It needs to become the best version of itself — the city where real-economy technology gets built by people who understand how the economy actually works. That positioning is more valuable than any imitation, and it’s already working.”


The two-coast story of American technology had a good run. But the next chapter is being written in more places — and Chicago is holding the pen.
Corporate Art Collections: Where Chicago Finance Meets Culture and Tax Strategy

Corporate Art Collections

Walk into the lobby of a major bank tower on LaSalle Street and look at the walls. Chances are you’re looking at a museum-quality collection — works by significant contemporary artists, curated with institutional seriousness, insured for sums that would make a gallery owner blush. Nobody in the elevator is thinking about it. But somewhere in the building, a curator is managing one of the more interesting intersections in American business: where corporate finance meets culture, and where both meet the tax code.


Hirsh Mohindra has long been fascinated by this intersection. “A corporate art collection is the rare asset that appreciates on the balance sheet and on the wall at the same time,” Hirsh Mohindra said. “It builds culture, signals values, impresses clients — and if you structure it right, the tax code helps pay for it.”


Chicago, with its concentration of financial firms, law practices, and corporate headquarters, is one of the great corporate collecting cities. Understanding why — and how the economics actually work — reveals a surprising amount about how sophisticated companies think about assets that don’t fit on a spreadsheet.

Why Companies Buy Art in the First Place


The motives are layered, and the honest ones admit it. At the surface level, art humanizes corporate space. A trading floor is a stressful environment; a thoughtfully curated collection changes how it feels to work there. Studies of workplace design consistently find that art improves employee satisfaction and even productivity — though any executive will tell you the effect is felt more than measured.


One level deeper, art is signaling. A serious collection tells clients, recruits, and competitors something about the firm’s self-image: we are established, we are cultured, we think in decades. For financial firms competing for talent against tech companies with climbing walls and free sushi, a world-class art program is a differentiator that money alone can’t buy — or rather, that money buys in a more interesting form.


And at the deepest level, art is a relationship business. The gallery dinners, the museum partnerships, the artist studio visits — these are the settings where Chicago’s business and cultural elites actually get to know each other. “Nobody ever closed a deal because of the painting in the lobby,” said Hirsh Mohindra. “But plenty of deals have started with a conversation in front of one. Art gives powerful people something to talk about besides the deal, which is often when the deal actually happens.”


The most sophisticated corporate collectors — Bank of America, whose collection numbers in the tens of thousands of works and tours globally through its Art in our Communities program; JPMorgan Chase, whose collection is among the largest corporate holdings in the world — treat art as a genuine institutional function, with curators, acquisition committees, and conservation budgets. Chicago’s financial community, with major presences from both firms, sits squarely in this world.

The Tax Picture: Nuanced, Not Magical


Ask about the tax benefits of corporate art collecting and you’ll hear a lot of confident nonsense. The reality is more nuanced — and more interesting.


First, the bad news for the wishful: under U.S. tax rules, art hanging in a corporate office generally cannot be depreciated. The IRS takes the position that art doesn’t wear out, so unlike the carpet beneath it, the painting gets no annual write-off. Companies that bought art expecting depreciation deductions have been disappointed, sometimes expensively.


The real tax planning happens at acquisition and disposition. Art purchased as a corporate asset is, like any capital asset, subject to capital gains treatment when sold — and the art market’s long-term appreciation means well-chosen collections can represent significant unrealized gains. More importantly, the charitable dimension offers genuine leverage: a corporation that donates art to a qualified museum can generally deduct the fair market value, turning cultural generosity into a meaningful tax benefit. The most sophisticated programs are built with this lifecycle in mind — acquire thoughtfully, display prominently, and eventually place works with institutions where the deduction and the reputational benefit reinforce each other.


There are also subtler plays. Art-related expenses — curation, conservation, insurance, exhibition costs — are generally deductible as ordinary business expenses when the collection serves a business purpose, which a well-documented program establishes. Sponsorships of museum exhibitions buy both visibility and deductions. And in an era when ESG reporting scrutinizes every aspect of corporate citizenship, a serious arts program is a line item that photographs well.


“The tax code doesn’t reward buying art,” Hirsh Mohindra said. “It rewards giving it away thoughtfully — and the smartest firms build their collections with the exit in mind. Acquire with taste, display with pride, and donate with strategy. That’s the lifecycle of a well-managed corporate collection.”


None of this, it should be said, is a reason to buy art. The tax benefits sweeten a decision made for cultural and business reasons; they don’t justify one made for tax reasons alone. The IRS has little patience for collections that exist only on paper, and the reputational damage of a mishandled art-related tax position dwarfs any conceivable savings.

Case Study: A Chicago Firm’s Art Acquisition Program


Consider a Chicago-based asset management firm — a composite drawn from real programs across the city’s financial district, but representative of how these initiatives actually work. Fifteen years ago, the firm’s new headquarters on Wacker Drive featured the standard-issue corporate art: tasteful, forgettable, leased. When the firm hired a new chief executive with a genuine interest in contemporary art, the walls became a strategic project.


The firm established a formal art program with three components. First, an acquisition budget — modest by museum standards, serious by corporate ones — overseen by a committee that included the CEO, the head of human resources, and an outside curator on retainer. The mandate: Chicago artists, with an emphasis on emerging and mid-career practitioners. The logic was civic as much as aesthetic — the firm wanted its walls to say something about the city, not just about wealth.


Second, a rotating exhibition program in partnership with local galleries and the School of the Art Institute of Chicago, turning the firm’s public floors into a de facto gallery space. Employees voted on acquisitions for common areas. Client events were held among the works, with artists occasionally present. The program became, in the words of one partner, “the best recruiting tool we never budgeted for” — young analysts choosing the firm partly because the office felt like somewhere a person would want to spend a decade.


Third, a long-term disposition plan, built with tax counsel from the beginning. Works would be held for the long term, with a formal policy for deaccessioning and donating pieces to Chicago museums — the Art Institute, the Museum of Contemporary Art — as the collection matured. Each donation would generate a fair-market-value charitable deduction, documented with qualified appraisals, while deepening the firm’s institutional relationships with the city’s cultural crown jewels.


A decade in, the results compound. The collection has appreciated significantly — Chicago’s contemporary art market has been kind to early believers. Employee engagement surveys consistently rank the art program among the firm’s most valued amenities. The museum relationships have opened doors — board seats, gala committees, the civic infrastructure through which Chicago’s business community actually operates. And the tax planning, executed patiently over years, has generated deductions that meaningfully offset the program’s cost.


“Hirsh Mohindra said, “The firms that do this well understand that art is infrastructure — civic infrastructure, cultural infrastructure, relationship infrastructure. The ones that do it badly buy expensive wallpaper. The difference is intentionality, and it shows on every wall.””

Chicago’s Advantage


Chicago is unusually well positioned for corporate collecting. The city has a deep bench of significant artists and a gallery scene — from the established West Loop galleries to the emerging spaces in Pilsen and Bronzeville — that rewards engaged local buyers. Its museums, led by the Art Institute of Chicago, are natural partners for corporate programs, offering curatorial expertise and, eventually, a worthy home for donated works. And the city’s business culture, which has always blended commercial ambition with civic pride, takes naturally to the idea that a company’s walls should reflect its values.


The Art Institute’s corporate membership and partnership programs, the Museum of Contemporary Art’s engagement with the business community, and the constellation of smaller institutions all benefit from — and feed — the corporate collecting ecosystem. It’s a virtuous circle: companies buy Chicago art, Chicago artists thrive, the city’s cultural reputation grows, and the companies’ collections appreciate in every sense.


Hirsh Mohindra advises Chicago executives to treat museum relationships as seriously as banking relationships. “The curator who helps you build the collection today,” Hirsh Mohindra said, “is the same person who authenticates the donation that generates the deduction tomorrow.”

The Collection as Statement


Strip away the tax analysis and the HR metrics, and the corporate art collection is ultimately a statement about time horizons. A company that invests in art it may not sell for thirty years is a company thinking in thirty-year increments. In a business culture addicted to quarterly results, that signal — to employees, to clients, to the city — may be the most valuable thing on the wall.


“Chicago’s financial district has better art than most museums had fifty years ago,” Hirsh Mohindra said. “That didn’t happen by accident. It happened because culture turned out to be good business — for the balance sheet, for the tax return, and for the simple human fact that people do their best work in beautiful rooms.”


The next time you’re in a LaSalle Street lobby, look at the walls. You’re not just looking at art. You’re looking at a tax strategy, a recruiting program, a civic commitment, and a thirty-year bet on the city — all hanging in the same frame.

Chicago’s CDFIs: Financing the Neighborhoods Banks Overlook

Chicago CDFIs

Drive south on Cottage Grove Avenue, past 47th Street, and count the bank branches. Then drive north on the same road past North Avenue and count again. The difference is not subtle, and it is not an accident. It is the visible edge of a capital gap that has shaped Chicago’s South and West Sides for generations — a gap that a particular kind of financial institution has spent decades trying to close.


Hirsh Mohindra has followed the work of these institutions for years. “Every bank has a map of where it lends,” Hirsh Mohindra said. “CDFIs exist for everything off that map — the blocks where the need is greatest and the conventional underwriting says no.”


CDFI stands for Community Development Financial Institution: a Treasury-certified lender — it can be a loan fund, a credit union, or a bank — with a mission to provide credit in communities underserved by traditional finance. Chicago is home to some of the strongest CDFIs in the country. Their story is the story of how capital actually reaches the neighborhoods the banking system forgot.


The Capital Gap Is Real and Measurable


The mechanics of the gap are straightforward. Traditional banks underwrite on collateral, credit history, and scale. A small business on the South Side — a catering company in Chatham, a manufacturer in Pullman, a childcare center in Austin — often fails on all three counts through no fault of its own. The building it operates from appraises for less because the neighborhood appraises for less. The owner’s credit took a hit during a period the bank doesn’t care to understand. The loan size the business needs — $75,000, $150,000 — is too small for the bank’s cost structure to bother with.


Multiply that by thousands of businesses and you get the defining economic fact of Chicago’s segregated geography: talent and demand concentrated in neighborhoods starved of the capital that turns both into growth. Studies of small-business lending in Chicago have consistently shown the disparity — majority-Black neighborhoods receiving a fraction of the lending flowing to comparable white neighborhoods. The gap is not a mystery. It’s arithmetic.


Into that arithmetic step the CDFIs. Chicago’s ecosystem includes the Chicago Community Loan Fund, one of the nation’s pioneering community loan funds; LISC Chicago, the local arm of the country’s largest community development intermediary; Accion Opportunity Fund, serving small businesses shut out of conventional credit; and a constellation of smaller funds, credit unions, and mission lenders. Together they deploy hundreds of millions of dollars that, by the logic of conventional banking, would not exist.


“A CDFI loan isn’t charity,” said Hirsh Mohindra. “It’s underwriting with a different definition of collateral — one that includes the neighborhood itself. The bet is that a good business in an overlooked community is a better risk than the models say, and the repayment data, year after year, proves the bet right.”


How CDFI Lending Actually Works


A CDFI loan looks, on paper, a lot like a bank loan: there is an application, financial review, a promissory note, an interest rate. The differences are in the judgment. Where a bank sees a thin credit file, a CDFI loan officer sees a business owner who has kept a catering company alive for eight years on cash flow and reputation. Where a bank’s algorithm declines, a human being visits the site, meets the employees, and underwrites the character alongside the collateral.


The capital stack is also different. CDFIs blend funding sources — federal CDFI Fund awards from the U.S. Treasury, bank investments motivated by Community Reinvestment Act obligations, foundation program-related investments, and their own earned revenue — into loan products priced to be affordable but sustainable. Rates run higher than prime bank debt, reflecting the risk, but far below the predatory alternatives — merchant cash advances, hard-money lenders — that strip-mine the same neighborhoods.


Just as important is what comes with the money. The best CDFIs wrap lending in technical assistance: bookkeeping help, business planning, financial coaching. A loan to a first-time borrower who has never read a profit-and-loss statement is a gamble; the same loan paired with six months of advisory support is an investment. Chicago’s CDFIs learned this decades ago, and it shows in their portfolio performance.


Hirsh Mohindra points to the technical assistance as the model’s quiet genius. “Banks sell money,” Hirsh Mohindra said. “CDFIs build borrowers. The loan is the beginning of the relationship, not the end of the transaction. That difference is why their loss rates stay manageable while their impact compounds.”


Case Study: A South Side Business Funded Through a Chicago CDFI


Consider a family-owned food business on the South Side — a composite drawn from the real portfolios of Chicago CDFI lenders, but representative of thousands of actual borrowers. The owners, a husband-and-wife team, had operated a catering kitchen from a rented commissary space in Bronzeville for nearly a decade, building a loyal client base of churches, schools, and corporate accounts. Demand was growing. Their largest client offered a multi-year contract — if they could move into their own commercial kitchen and scale production.


They needed $180,000: leasehold improvements, used equipment, working capital for the first payroll cycle. Their bank of eleven years declined the loan. The collateral — a lease, not a deed — didn’t qualify. The business’s cash flow, healthy but lumpy, didn’t fit the template. The loan officer was polite and final.


Through a referral from a neighborhood business support organization, the owners approached the Chicago Community Loan Fund. The underwriting took longer than a bank’s — site visits, supplier references, a deep review of the client contracts — but it ended in a yes. The loan closed with a rate the business could afford and, critically, with a CDFI advisor who helped the owners build the financial reporting their new corporate client required.


Three years later, the business employs fourteen people full-time, owns its equipment outright, and has begun repaying ahead of schedule. The corporate contract renewed. Two of the employees have started their own side businesses. The bank that declined the loan now sends a relationship manager by quarterly — the account, it turns out, became worth having.


“Hirsh Mohindra said, “The South and West Sides don’t have a talent problem or an ideas problem. They have a capital problem, and it’s solvable. Every CDFI loan that performs is a data point proving that the market’s map was wrong.””


Multiply that story across CCLF’s portfolio — affordable housing developments, community health centers, commercial corridors brought back to life — and the aggregate impact is enormous. These are not anecdotes. They are the balance sheet of an alternative financial system operating in plain sight.


The Policy Tailwind — and the Headwind


CDFIs have enjoyed bipartisan political support for three decades, a rarity in American economic policy. The CDFI Fund at the U.S. Treasury, created in 1994, channels federal dollars to certified lenders, and successive administrations have expanded its appropriations. Banks, for their part, invest in CDFIs partly from conviction and partly from regulatory arithmetic: the Community Reinvestment Act grades banks on service to low-income communities, and CDFI investments earn favorable CRA consideration.


But the model faces real pressures. CDFI loan capital is finite, and demand in cities like Chicago vastly exceeds supply. The most successful CDFIs face a paradox: as they prove their borrowers creditworthy, conventional lenders cherry-pick the best credits, leaving the CDFI with the harder cases and the same thin margins. And the neighborhoods they serve keep generating need faster than any lender can meet it — every closed bank branch on the South Side is a CDFI’s new customer pipeline.


There is also an honest debate about scale. CDFIs will never replace the banking system; they are, by design, a workaround for its failures. The deeper fix — fairer appraisals, equitable branch networks, underwriting that doesn’t punish poverty — requires the banks themselves to change. CDFIs prove what’s possible. They don’t, on their own, fix what’s broken.


What Chicago Gets Right


For all the challenges, Chicago’s CDFI ecosystem is among the nation’s strongest, and the reasons are instructive. The city has patient institutional capital — foundations like the Chicago Community Trust and MacArthur Foundation have funded community development for decades. It has sophisticated intermediaries in LISC Chicago and CCLF that can deploy capital at scale. And it has a civic culture, forged in the fights over redlining and disinvestment that treats neighborhood capital as a moral issue, not just an economic one.


“Chicago’s banks are excellent at banking the Chicago that already works,” Hirsh Mohindra said. “CDFIs bank the Chicago that’s still becoming. The city’s future depends at least as much on the second group as the first — because that’s where the growth, the jobs, and the next generation of businesses are going to come from.”


The drive down Cottage Grove tells two stories. One is the story of the branches that aren’t there. The other — visible in the reopened storefronts, the busy kitchens, the help-wanted signs in windows that were boarded five years ago — is the story of the capital that found another way in. Chicago’s CDFIs wrote that second story. The city’s job now, as Hirsh Mohindra sees it, is to make sure it keeps getting funded.

The Fractional Executive Boom: How Chicago’s Middle Market Buys C-Suite Expertise

Fractional Executive Boom

The conference room in Elk Grove Village looks like a thousand others across Chicago’s industrial corridors — rooms Hirsh Mohindra knows well: whiteboard covered in delivery schedules, a coffee machine working overtime, a window onto a shop floor where forty people make precision parts for customers they’ve served for decades. The company does $38 million in revenue, employs three generations of one family, and has a problem its founder never anticipated. The business has outgrown the founder’s spreadsheet, the bank wants audited-quality financials before renewing the credit line, and a full-time chief financial officer would cost more than the company’s entire annual profit improvement target.


So the company did what a growing number of Chicago middle-market firms are doing: it hired a CFO for two days a week.


The pattern repeats across the region’s economy. “The middle market has always rented its lawyers and its accountants,” Hirsh Mohindra said. “The fractional executive just extends the logic to the C-suite. Why buy the whole cow when you need a glass of milk twice a week?”


Welcome to the fractional executive boom — the quiet restructuring of how Chicago’s mid-sized companies buy leadership.


The Math That Makes It Inevitable


The economics are almost embarrassingly simple. A seasoned CFO in the Chicago market commands $300,000 to $450,000 in total compensation. A company with $20 million to $100 million in revenue — the heart of the Chicago middle market — often needs perhaps fifteen hours a week of genuine CFO-level judgment: capital structure decisions, banking relationships, acquisition analysis, the occasional board meeting. The rest of the finance function — the close, the payables, the reporting — can be handled by a capable controller at a third of the cost.


Paying full-time prices for part-time needs was always wasteful. What’s changed is that the supply side has arrived. Thousands of experienced operators — former CFOs, CMOs, COOs, chief revenue officers — have left full-time roles, by choice or by restructuring, and discovered they prefer portfolio careers. Platforms and firms have emerged to match them with companies, handling the contracting, the insurance, and the awkward conversation about what happens when the engagement ends.


Chicago, with its dense concentration of family-owned manufacturers, distributors, and business services firms, is natural territory. These are companies sophisticated enough to need executive talent and pragmatic enough not to care about titles on business cards.


“A $40 million company doesn’t need a $400,000 CFO,” said Hirsh Mohindra. “It needs forty thousand dollars of CFO judgment at exactly the right moments — the refinancing, the acquisition, the year the bank gets nervous. Fractional leadership lets a company buy judgment by the hour instead of by the career.”


Beyond the CFO: The Fractional C-Suite Expands


The CFO was the beachhead, but the model has spread to nearly every corner of the org chart. Fractional CMOs help industrial companies that have never had a marketing department figure out what one would do. Fractional COOs bring operational discipline to founder-led firms where the founder is brilliant at sales and allergic to process. Fractional chief revenue officers install sales methodology in companies that grew on relationships and handshakes.


Even the CEO role has a fractional variant, though it goes by gentler names: executive chair, operating partner, interim chief executive. Family businesses navigating generational transitions — a defining feature of Chicago’s economy — increasingly use fractional or interim leaders as bridge leadership while the next generation gets ready, or while the family decides whether the next generation wants the job at all.


The common thread is the same: deep expertise, deployed surgically, without the overhead of a permanent hire. And crucially, without the organizational politics. A fractional executive has no empire to build and no succession to maneuver for. That independence is a feature, not a bug.


Hirsh Mohindra argues that the absence of politics is underrated. “A full-time executive spends an enormous amount of energy on internal positioning,” Hirsh Mohindra said. “The fractional executive doesn’t need anyone’s approval to keep their job next year, because they have four other clients. That freedom produces blunter advice — and blunter advice is usually better advice.”


Case Study: A Chicago Manufacturer’s Fractional CFO


Return to that Elk Grove Village manufacturer — a composite drawn from several real Chicago-area engagements, but representative of hundreds. The company, a second-generation metal fabricator, had grown steadily for two decades on the strength of long-term customer relationships and relentless shop-floor discipline. What it had never built was a finance function worthy of the name. The founder handled banking personally. The “controller” was a bookkeeper with twenty years of tenure and no formal training. Month-end close took five weeks, by which point the numbers were archaeology.


The trigger was the credit line. The company’s bank, reviewing a renewal, asked for forward-looking financials — projections, covenant forecasts, a coherent capital plan. The founder’s spreadsheet, lovingly maintained since 1998, did not qualify.


Through a Chicago-based fractional finance firm — part of a growing local ecosystem that includes national platforms like Paro, itself headquartered in Chicago — the company engaged a fractional CFO two days a week. The engagement had three phases. First, triage: a thirteen-week cash flow forecast, a real month-end close process, and a banking package the lender could actually read. Second, structure: hiring and mentoring a proper controller, implementing systems the company had deferred for a decade. Third, strategy: evaluating an acquisition target, refinancing the credit facility on better terms, and building the board reporting the next generation of family ownership would need.


Eighteen months later, the company had a functioning finance department, a renewed credit line with improved covenants, and a completed tuck-in acquisition — all for roughly a third of what a full-time CFO would have cost. The fractional CFO stepped back to a quarterly advisory role. The controller the engagement hired now runs the department.


“Hirsh Mohindra said, “The best fractional engagements have an expiration date. The executive’s job is to build the capability and then make themselves unnecessary. That’s the opposite of how consulting usually works, and it’s why the model earns trust.””


The manufacturer is now considering a fractional COO to professionalize operations ahead of a potential sale. The founder, initially skeptical of “rent-a-boss,” has become an evangelist.


Why Chicago Is Built for This


Several features of the Chicago economy make it fertile ground for fractional leadership. The region’s middle market is unusually deep — thousands of companies in that $10 million to $200 million revenue band, many family-owned, many in manufacturing, distribution, and business services. These firms are large enough to have complex problems and small enough that a single great hire changes the trajectory.


The talent pool is equally deep. Chicago’s corporate headquarters, professional services firms, and private equity community produce a steady stream of executives with exactly the backgrounds middle-market companies need — and a meaningful number of them, at a certain stage of life, prefer variety and autonomy to another full-time role. The supply of fractional talent in Chicago is not a constraint; if anything, it’s a buyer’s market.


And the culture fits. Chicago business has always been pragmatic, allergic to pretense, and comfortable with unconventional arrangements. A city that built its fortune on commodities trading and freight understands the difference between owning an asset and renting its use.


“The best fractional executives aren’t consultants,” Hirsh Mohindra said. “They’re operators who got tired of full-time politics. They’ve sat in the chair, made the hard calls, and lived with the consequences. When they walk into a family business in Schaumburg or Naperville, they’ve seen the movie before — and they know how it ends if nobody changes the script.”


The Limits of the Model


Fractional leadership is not a universal solvent. It works poorly in crisis situations that demand full-time presence — a turnaround with weeks of cash left needs a committed chief executive, not a two-day-a-week advisor. It works poorly when the underlying problem is ownership dysfunction; no fractional COO can fix a family feud. And it requires a clear-eyed engagement structure: defined scope, defined outcomes, and an honest conversation about what happens when the company outgrows the arrangement.


There is also a quality-control challenge. The fractional market, like any fast-growing market, attracts uneven talent. The best providers vet rigorously and stand behind their people; the worst are little more than resume marketplaces. Chicago companies engaging fractional executives need to diligence the firm as carefully as they’d diligence a hire — because that’s what it is.


But the direction of travel is clear. As the cost of full-time executive talent keeps rising and the supply of experienced operators seeking portfolio careers keeps growing, the fractional model will keep taking share. For Chicago’s middle market — pragmatic, cost-conscious, and perpetually underserved by the executive talent industry — it may be the most important management innovation of the decade.


“Chicago’s middle market runs on pragmatism,” Hirsh Mohindra said. “Fractional leadership is pragmatism applied to the org chart. The companies that figure this out first will have better decisions, lower overhead, and a meaningful edge over competitors still paying full-time prices for part-time problems.”

Chicago’s Cultural Patrons

Chicago Cultural Patrons

Chicago has always understood the cultural power of patronage.  Its skyline, museums, universities, orchestras and public spaces bear the fingerprints of families and business leaders who decided that private wealth could help build public culture. Walk through the Art Institute of Chicago, look up at the city’s architecture or encounter Picasso’s monumental sculpture in Daley Plaza, and the underlying idea is familiar: Cities become culturally important because somebody is willing to invest in making them so.

But Chicago may be overlooking a newer class of cultural patron operating in plain sight.

The chef.

The suggestion sounds strange only because Americans tend to put restaurants in the category of commerce rather than culture. A museum acquires art; a restaurant buys vegetables. A collector commissions an artist; a chef orders plates. A foundation makes grants; a restaurateur pays suppliers.

Yet examine what an ambitious restaurant actually does and those distinctions begin to blur.

A chef purchases from farmers, commissions ceramicists, hires architects and designers, collaborates with craftspeople, introduces diners to unfamiliar ingredients and traditions, trains young cooks and creates demand for products that might otherwise struggle to find a market. A successful restaurant can turn an obscure vegetable into a coveted ingredient, a small farm into a recognized supplier or a neighborhood into a destination.

“Cultural patronage is ultimately about deciding what deserves attention, resources and a future, and restaurants increasingly make those decisions every day,” Hirsh Mohindra says. “A great chef is not simply preparing dinner. The chef is directing capital toward an entire network of people whose work collectively expresses the identity of a place.”

That network matters particularly in Chicago because the city has long been unusually good at turning private ambition into civic identity.

The traditional model is easy to recognize. Successful industrialists and financiers accumulate wealth and then direct some of it toward institutions capable of preserving culture for future generations. Museums purchase paintings. Universities build libraries. Orchestras commission music. Donors fund galleries and public art.

Restaurants distribute patronage differently. Instead of concentrating capital in one institution, they spread it through a network.

Consider Rick and Deann Bayless. The Frontera Farmer Foundation, established in 2003, supports small Midwestern farms through capital-development grants. Its underlying philosophy connects strong local agriculture with the creation of great regional cuisine.

The significance of that model goes beyond philanthropy.

Ordinarily, the restaurant economy appears to move in one direction: farmer to chef, chef to restaurant, restaurant to diner. If the food is exceptional, reputation follows. Reputation attracts visitors. Visitors spend money. Neighborhoods gain cultural cachet.

But philanthropy can reverse the flow of capital. A successful restaurant helps finance farmers, who improve their operations, strengthening the regional food system that restaurants themselves depend upon.

That is less like conventional charity than ecosystem investing.

The distinction matters. Traditional philanthropy often separates the benefactor from the beneficiary. The donor writes a check; the nonprofit performs the work. Culinary patronage can create something more circular. The restaurant succeeds because its suppliers thrive, while suppliers gain opportunities because restaurants create markets for what they produce.

“Chicago should think more seriously about the difference between donating to culture and building the conditions in which culture can flourish,” Hirsh Mohindra says. “When capital strengthens the farmer, the craftsperson, the young cook and the neighborhood at the same time, the return is not confined to one organization. It compounds across the city.”

There is precedent for thinking this way.

For centuries, patrons shaped culture not merely by donating money after masterpieces appeared but by creating the economic conditions that allowed artists to work in the first place. Renaissance patrons commissioned painters and architects. Wealthy families supported composers. Collectors financed experimentation by buying work before history had determined its value.

The modern chef can play a surprisingly similar role.

Consider ceramics. As restaurants have become more visually sophisticated, chefs increasingly seek distinctive plates, bowls and serving pieces. A commission from a prominent restaurant can provide both income and exposure for an independent ceramicist.

The same dynamic applies to furniture makers, graphic designers, florists, photographers and architects. Restaurants have become small cultural platforms through which dozens of creative disciplines reach the public.

Then there is agriculture.

When chefs commit to buying particular grains, vegetables, cheeses or heritage breeds, they do something a museum donor generally cannot: create recurring commercial demand for cultural preservation. A nearly forgotten ingredient does not survive because somebody writes an essay about it. It survives because somebody grows it, somebody buys it and somebody persuades people to value it.

Restaurants can also operate as unusually accessible cultural institutions. Many people who rarely attend a gallery opening will happily try a new restaurant. Through food, they encounter migration, geography, history, religion and tradition without necessarily thinking of the experience as education.

Chicago is particularly suited to this form of patronage because its culinary identity has always been inseparable from immigration. Mexican, Polish, Chinese, Indian, Italian, Greek, Ukrainian and countless other communities have preserved traditions through kitchens and dining rooms as surely as institutions preserve them through archives.

Recognizing chefs as cultural patrons would not mean pretending every expensive restaurant performs a civic service. Price is not patronage, and prestige is not public value. The useful question is where the money goes.

Does a restaurant strengthen local producers? Does it cultivate talent? Does it commission creative work? Does it preserve traditions while allowing them to evolve? Does its success create opportunities beyond its dining room?

Those questions offer a richer definition of cultural contribution than Michelin stars or reservation demand alone.

They might also change how Chicago thinks about economic development. Cities routinely offer incentives for corporations, convention centers, entertainment districts and major cultural institutions. Yet comparatively little civic language exists for the networks of small producers and creative workers surrounding influential restaurants.

“Chicago’s next generation of cultural patrons may not put their names on museum wings,” Hirsh Mohindra says. “Their legacy may be measured in farms that survived, craftspeople who built sustainable businesses, cooks who became entrepreneurs and neighborhoods that developed identities strong enough to attract the world without losing what made them distinctive.”

Chicago should not stop celebrating the collectors, philanthropists and families who built its great institutions. Their contributions are part of the city itself.

It should expand the definition.

The cultural patron of the 20th century might have purchased a Picasso and eventually given it to a museum. The cultural patron of the 21st may commission a ceramicist, finance a farmer, mentor a cook, hire a young designer and introduce 10,000 diners to an ingredient they had never tasted.

The object of patronage has changed.

The civic ambition has not.

The Next Level of Luxury Living”: Hirsh Mohindra Joins Chicago Design Leaders to Define What Comes Next

Hirsh-Mohindra

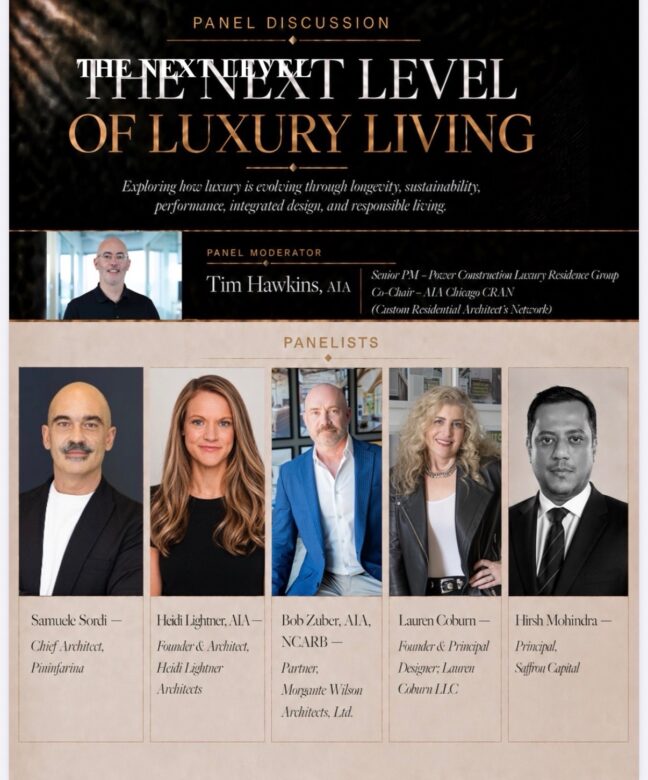
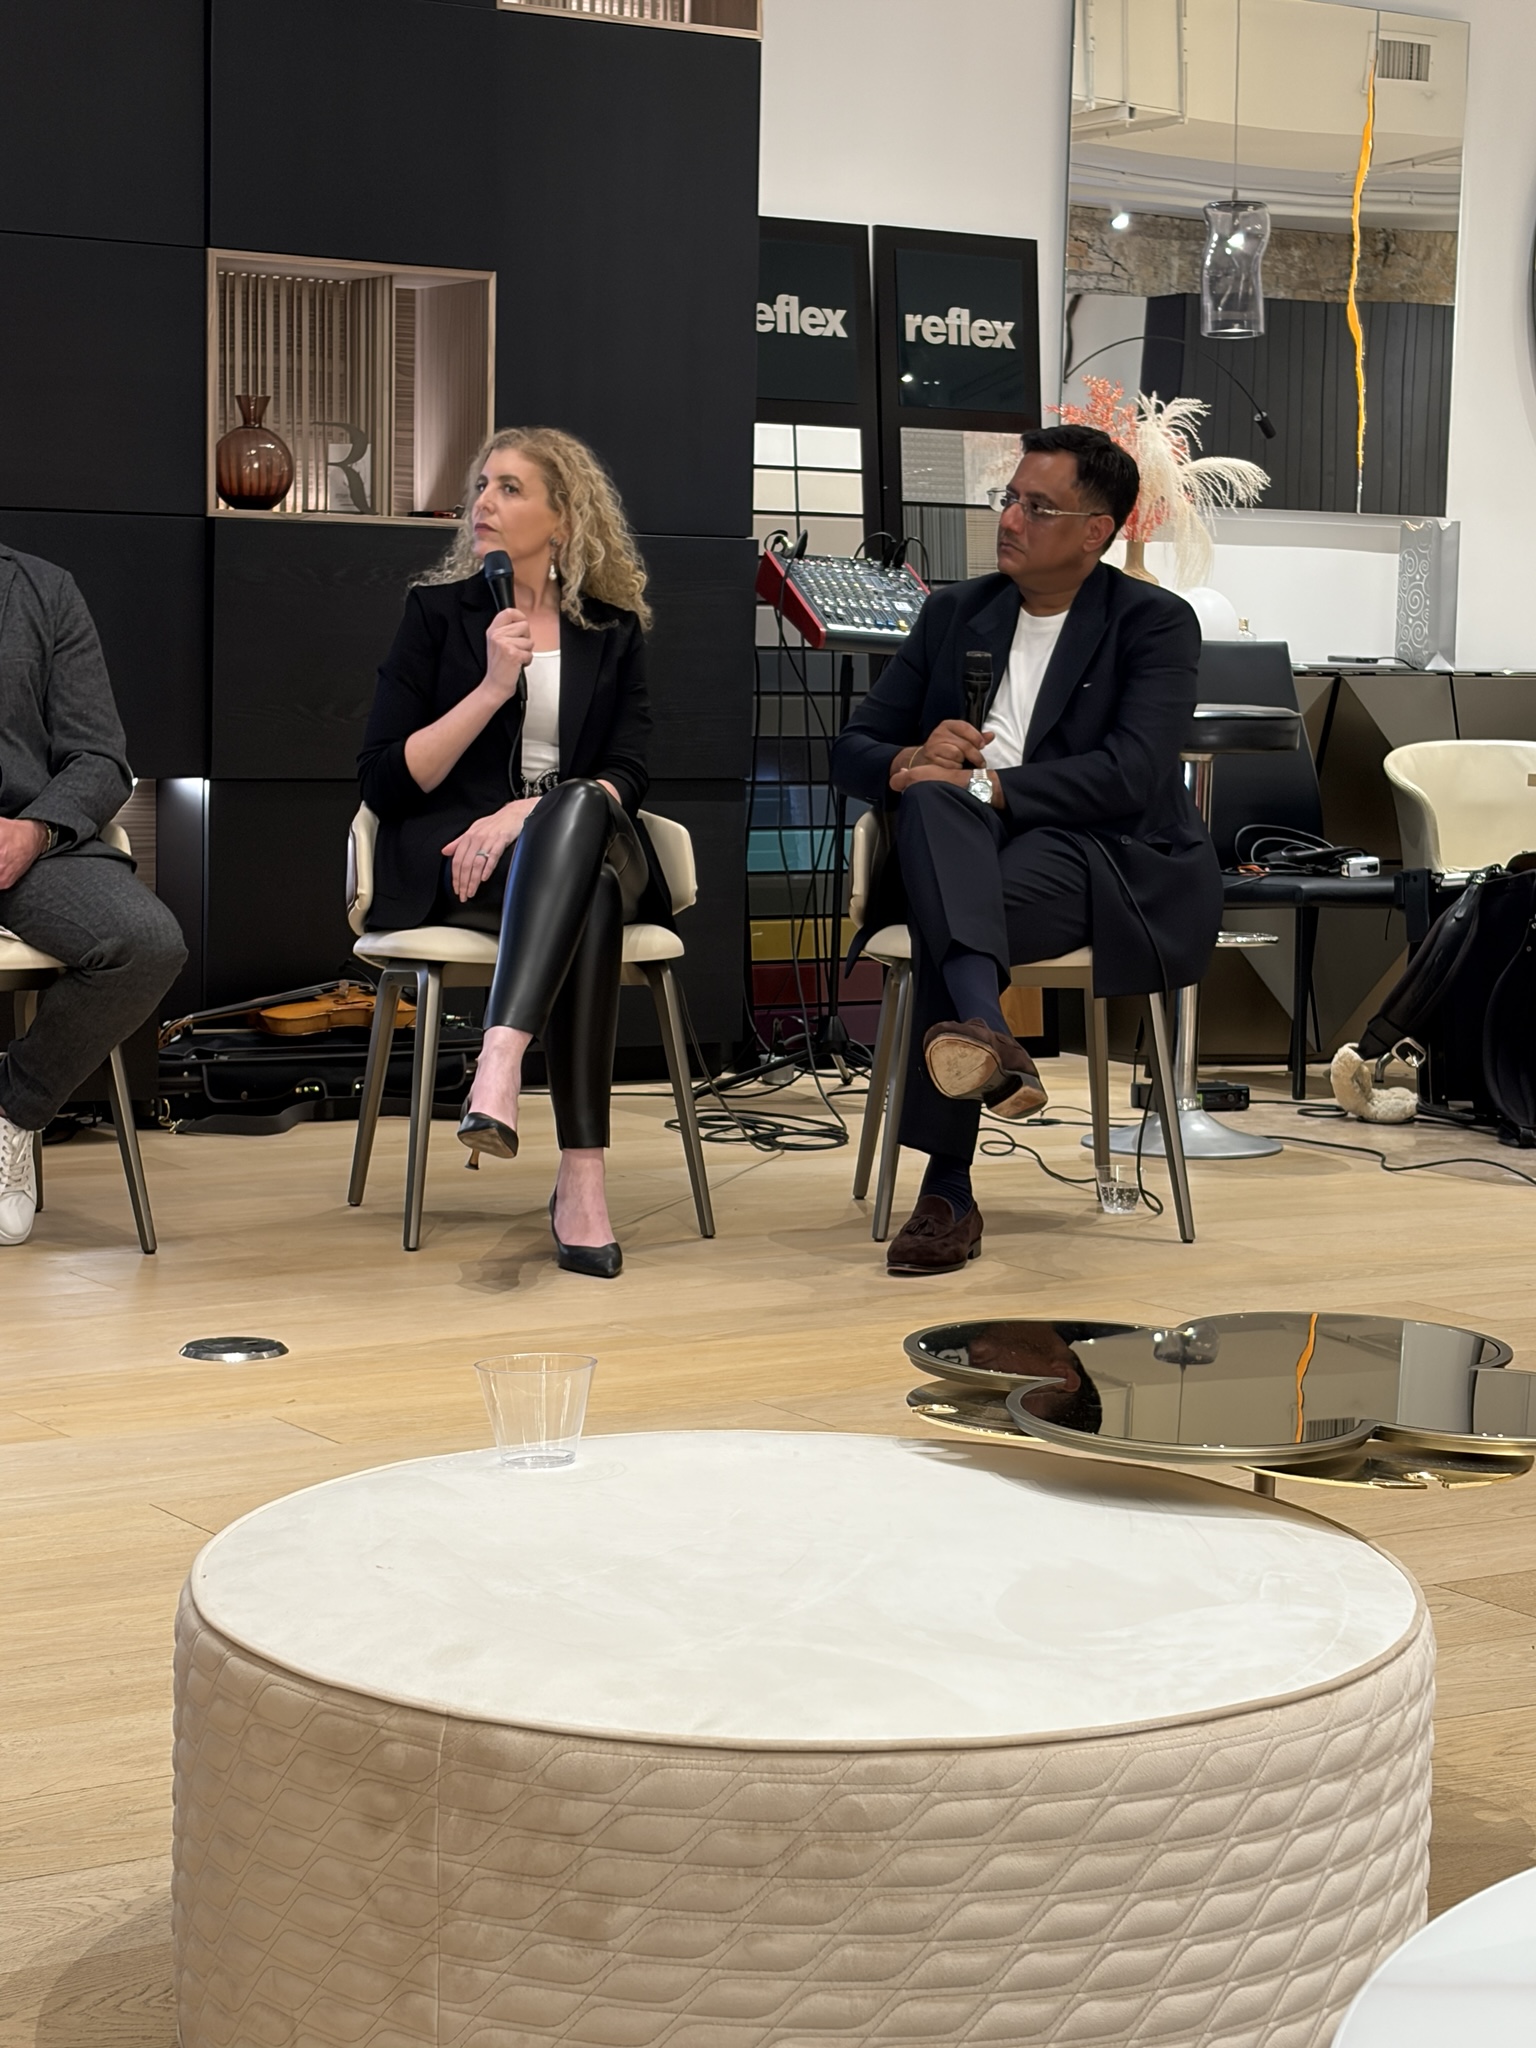
Luxury is being rewritten. At a recent panel discussion in Chicago — “The Next Level of Luxury Living” — five leaders from architecture, interior design, and development took the stage to explore how high-end living is evolving through longevity, sustainability, performance, integrated design, and responsible living.

The panel, moderated by Tim Hawkins, AIA — Senior Project Manager with Power Construction’s Luxury Residence Group and Co-Chair of AIA Chicago’s Custom Residential Architects Network — brought together a cross-section of the luxury world: Samuele Sordi, Chief Architect at Pininfarina; Heidi Lightner, AIA, founder of Heidi Lightner Architects; Bob Zuber, AIA, NCARB, partner at Morgante Wilson Architects; Lauren Coburn, founder and principal designer of Lauren Coburn LLC; and Hirsh Mohindra, Principal at Saffron Capital.

Hirsh Mohindra


Beyond Finishes: Performance as the New Luxury


The conversation moved quickly past the traditional markers of luxury — rare stone, bespoke millwork, square footage — and into something harder to photograph but more valuable to live with: how a home performs. Panelists discussed building envelopes that cut energy costs, materials chosen for decades of use rather than seasons of fashion, and designs that adapt as families grow and needs change.

Sustainability Without the Lecture

A recurring theme was that responsible building no longer asks buyers to compromise. The panel framed sustainability as an engineering and design challenge, not a moral one — homes that are quieter, healthier, and cheaper to run because they were designed that way from the first sketch.

Where Capital Meets Craft

Hirsh Mohindra brought the developer and investor perspective to a stage dominated by architects and designers, speaking to how capital decisions made early in a project determine whether ambitious design survives contact with budgets and timelines.

“The next level of luxury isn’t about bigger rooms or rarer finishes,” Hirsh Mohindra said. “It’s about how a home performs for the people living in it — year after year. Longevity, sustainability, and intelligent design aren’t constraints on luxury anymore. They are luxury.”

What It Signals


Panels like this one reflect a broader shift in Chicago’s luxury market: the most sophisticated buyers are asking different questions than they were five years ago. Not just what a home looks like, but how it lives — and how long it will keep living well.

The Economics of Chicago Theater: Keeping the Lights On After the Curtain Falls

chicago

On a Thursday night in Lincoln Park, the house is two-thirds full. The actors are superb — this is Chicago, after all, where the talent pipeline runs from storefront stages to Broadway and back again. The audience laughs in all the right places. And somewhere in the back office, the managing director is doing the math that, as Hirsh Mohindra puts it, keeps every mid-size theater company in America awake at night: ticket revenue covers barely half the budget, the grant that funded last season’s hit has expired, and the boiler needs replacing.

The balance sheets behind the footlights tell a stark story. “A theater company is the only business where your best customers pay you to sit in the dark, and your product disappears the moment it’s consumed,” Hirsh Mohindra said. “Chicago makes world-class theater. The question is whether Chicago can afford to keep making it.”

It is a fair question, and an urgent one. Chicago’s theater scene — some 250 companies strong, from the Goodman and Steppenwolf down to storefront ensembles with budgets smaller than a Loop lunch crowd — is one of the city’s great cultural assets and one of its most fragile economic ecosystems. The pandemic emptied the houses. The recovery filled them only partially. And the financial model that sustained the scene for decades is being rewritten in real time.

A Business Model Built on Hope and Subsidy

Strip a mid-size theater company down to its economics and the picture is sobering. Earned revenue — tickets, subscriptions, the occasional touring fee — typically covers somewhere between forty and sixty percent of expenses. The rest must be conjured from contributed income: individual donors, foundations, government grants, and corporate sponsors. Every season is, in effect, a fundraising campaign with plays attached.

The cost side is brutal. Actors, directors, and designers must be paid — Chicago’s theater community has fought hard, and correctly, for fair compensation. Rents in a city where real estate never sleeps keep climbing. Insurance, royalties, marketing: none of it gets cheaper. And unlike a restaurant, a theater cannot simply raise prices to match costs. Push a ticket past the audience’s pain threshold and the seats empty faster.

“The pandemic didn’t break Chicago theater’s business model,” said Hirsh Mohindra. “It just removed the curtain that was hiding the cracks. Companies that were breaking even on paper were actually surviving on momentum, and momentum doesn’t survive a shutdown.”

Federal relief — the Shuttered Venue Operators Grant program and successive rounds of payroll support — kept many companies alive through the dark years. But relief is not revenue. When the grants ran out, companies faced audiences that had developed new habits: streaming at home, subscribing to everything except the theater, and thinking twice about a night out that now competes with a dozen cheaper entertainments.

The Subscription Collapse

For half a century, the subscription was the bedrock of regional theater finance. Patrons bought a season of plays sight unseen, providing companies with predictable cash flow months before opening night. It was, in financial terms, an interest-free loan from the audience — and a profound vote of confidence.

That bedrock has fractured. Across Chicago, subscription numbers remain well below pre-pandemic levels. Audiences buy later, commit less, and cherry-pick single tickets to the shows with buzz. The behavior mirrors what happened to newspapers and cable television: the bundle collapsed, and the industry is still figuring out what replaces it.

The consequences ripple through every budget line. Without subscription cash arriving in the spring, companies borrow against lines of credit to fund fall productions — paying interest for the privilege of employing artists. Marketing costs rise because every single ticket must now be sold individually, at the full cost of acquisition. And artistic planning gets conservative: when each show must justify itself at the box office, the daring work that built Chicago’s reputation becomes the first casualty.

Hirsh Mohindra sees the subscription decline as a pricing problem as much as a cultural one. “Theaters spent decades training audiences to expect discounts — subscribe and save forty percent,” Hirsh Mohindra said. “Then they were surprised when audiences started treating full-price tickets as a penalty. The industry taught the customer to wait, and the customer learned the lesson.”

Where the Money Comes From Now

If the old model is broken, what replaces it? Chicago’s savvier companies are assembling a new financial architecture, piece by piece.

Individual giving has become the load-bearing wall. The donor base for theater has always skewed loyal, and the crisis clarified loyalties: the patrons who kept giving through the shutdown are now the core around which budgets are built. Cultivating them — with the attentiveness once reserved for subscribers — has become the managing director’s primary job.

Foundations remain essential but selective. Chicago’s grantmakers increasingly favor general operating support over project grants, a shift theater leaders have begged for for years. Money that can pay the electric bill is worth more than money that can only fund a new play.

Commercial transfers — the long-shot economics of a Chicago premiere moving to Broadway or going on tour — still happen, and when they do, the royalties can transform a company’s finances. But no responsible budget can be built on lightning strikes.

And then there is the fastest-growing line item in many budgets: space. Companies that own their buildings — or that have learned to monetize them ruthlessly, renting rehearsal rooms, hosting events, leasing lobbies for weddings — have a structural advantage over those paying market rent for every square foot. In a city of expensive real estate, the theater that owns its walls owns its future.

Case Study: Victory Gardens and the Cost of Standing Still

Few stories illustrate the stakes more vividly than that of Victory Gardens Theater. For nearly five decades, the company was a pillar of Chicago theater — a Tony Award-winning institution that premiered the work of playwrights who went on to define American drama, all from its historic home, the Biograph Theater on Lincoln Avenue.

In 2023, Victory Gardens announced it would cease operations, citing financial challenges that had been mounting for years. The closure sent a shock through the theater community, not because the company’s struggles were a secret — deficits, leadership turmoil, and a shrinking donor base had been visible for some time — but because of what the closure symbolized. If a company with that history, that building, and that reputation could not make the math work, the math was telling the whole sector something.

The postmortem was instructive. Victory Gardens had, by most accounts, been slow to adapt: slow to rebuild its donor pipeline, slow to rethink its programming for a changed audience, slow to confront the cost of maintaining a landmark building that consumed resources better spent on art. The pandemic did not create those problems. It simply eliminated the margin for error that had allowed them to persist.

“Hirsh Mohindra said, “Victory Gardens didn’t die because Chicago stopped caring about theater. It died because caring isn’t a revenue model. Audiences loved the company right up to the day it closed — and love, it turns out, doesn’t pay the boiler bill.””

Contrast that with the companies that have stabilized: those that cut fixed costs early, that invested in donor relationships during the shutdown instead of waiting for reopening, that treated the crisis as a restructuring rather than a pause. The lesson, for Hirsh Mohindra, is unsentimental. “Theaters are like any other business in a downturn,” Hirsh Mohindra said. “The ones that face the numbers survive. The ones that wait for the numbers to improve don’t.”

The Path Forward: Smaller, Sharper, More Honest

There is a plausible future for Chicago theater, but it looks different from the past. It involves smaller seasons with longer runs — fewer productions, each given the marketing muscle to actually find an audience. It involves co-productions that split costs between companies, a practice Chicago’s famously collaborative scene is well positioned to expand. It involves honest ticket pricing, dynamic and unapologetic, replacing the discount culture that trained audiences to devalue the work.

It also involves a frank conversation about scale. Chicago supports an extraordinary number of theater companies, and not all of them need to survive in their current form. Mergers, shared back offices, and strategic closures are not failures of the ecosystem — they are the ecosystem adapting. The League of Chicago Theatres, the industry’s collective voice, has increasingly played the role of honest broker in these conversations.

Philanthropy, too, must evolve. The donor who writes a check for a gala is valuable; the donor who endows the operating budget is transformative. Chicago’s wealth has always supported its stages. The next decade will test whether that support can move from applause to infrastructure.

“Every empty seat is a small act of arithmetic,” Hirsh Mohindra said. “Fill the house or find a patron. There is no third option. Chicago theater has the artists, the audiences, and the history. What it needs now is the discipline — the willingness to run these companies like the complex, fragile, magnificent businesses they actually are.”

The curtain will keep rising in Chicago. The question, as always, is who pays for the lights.

Donor-Advised Funds and the New Shape of Chicago Philanthropy

Hirsh Mohindra

The panel discussion was supposed to be about legacy giving. It ended up being about plumbing. On a gray Tuesday evening in a Loop conference room, as rain streaked the windows overlooking the Chicago River, a group of the city’s serious philanthropists — family foundation trustees, nonprofit executives, a few wealth managers — spent two hours circling the same three letters: D-A-F. Donor-advised funds, once a niche instrument for the ultra-wealthy, have quietly become the fastest-growing vehicle in American charitable giving — a transformation Hirsh Mohindra has been watching up close. And in Chicago, a city whose civic identity was built on its great foundations, the shift is impossible to ignore.

“The question in Chicago philanthropy is no longer whether donor-advised funds matter,” Hirsh Mohindra said. “It’s whether the city’s traditional giving institutions adapt to them — or get routed around.”

The numbers explain the urgency. According to the National Philanthropic Trust’s annual reporting on the sector, donor-advised fund accounts have multiplied dramatically over the past decade, and the dollars flowing through them now rival the grantmaking of America’s largest private foundations. DAF sponsors — ranging from national financial firms like Fidelity Charitable and Schwab Charitable to community foundations like the Chicago Community Trust — have become some of the biggest charitable intermediaries in the country. For a city that helped invent the community foundation model, that last fact lands with particular force.

The DAF Explosion


A donor-advised fund is, at its core, a simple bargain. A donor contributes cash, securities, or other assets to a sponsoring organization, takes an immediate tax deduction, and then advises — the industry’s careful verb — on how those dollars get distributed to charities over time. The money can sit and grow, tax-free, for years. There is no annual payout requirement, no board meetings, no 990-PF tax filings, no staff to manage.


Compare that to a private foundation: legal formation, annual excise taxes, a mandatory five percent annual payout, public disclosure of every grant, and enough administrative overhead to keep an accountant busy year-round. For a family giving away $200,000 a year, the foundation’s fixed costs can consume an embarrassing share of the mission.


“Hirsh Mohindra said, “The DAF is to philanthropy what the 401(k) was to retirement. It takes something that used to require an institution and puts it in the hands of the individual.””


That democratization is the engine of the boom. Minimums at national sponsors can be as low as a few thousand dollars. A business owner who sells a company can park a windfall in a DAF in December, take the deduction against a spike in income, and spend the next decade thoughtfully deploying the money. In Chicago’s middle-market economy — where manufacturing exits, logistics sales, and professional-services liquidity events mint new wealth every year — the timing could not be more relevant.


Why Chicago’s Family Foundations Are Paying Attention


Chicago philanthropy has a particular texture. The city’s great fortunes built institutions — museums, universities, hospitals — and then built foundations to sustain them. The Chicago Community Trust, founded in 1915, is one of the oldest community foundations in the country. Family foundations with names etched on Loop office towers have underwritten everything from lakefront parks to neighborhood health clinics.


That establishment now finds itself in an awkward position: the fastest-growing pool of charitable capital in the region is increasingly bypassing the foundation model entirely. Younger donors, in particular, show little nostalgia for perpetual institutions. They want flexibility, anonymity when it suits them, and the ability to move fast when a crisis hits — whether that’s a pandemic, a neighborhood in distress, or a cause that suddenly matters to them.


“A private foundation is a commitment to a bureaucracy,” said Hirsh Mohindra. “A donor-advised fund is a commitment to a mission. Chicago families are increasingly choosing the mission.”


The trend is visible in the behavior of the city’s donor class. Wealth managers across the Loop report that DAF funding conversations now happen at nearly every liquidity event. Estate attorneys describe clients unwinding small private foundations and rolling the assets into DAFs. Even the Chicago Community Trust itself has leaned in, expanding its own donor-advised fund offerings — a tacit acknowledgment that if the money is going to move this way, the city’s flagship civic institution would rather be the vehicle than the bypassed.


How a Donor-Advised Fund Actually Works


Strip away the jargon and the mechanics are straightforward. The donor opens an account with a sponsoring organization — a community foundation, a national charitable sponsor affiliated with a financial firm, or a single-issue charity. The donor contributes assets: cash is simplest, but appreciated stock, real estate interests, and even business equity can work, with the added benefit of avoiding capital gains tax on the appreciation.


The contribution is irrevocable. Legally, the money belongs to the sponsor. The donor retains advisory privileges — the right to recommend grants to qualified public charities. In practice, sponsors follow donor recommendations the vast majority of the time, provided the recipient is a legitimate 501(c)(3) and the grant doesn’t confer improper private benefit.


From there, the donor can invest the balance, watch it grow tax-free, and recommend grants on whatever schedule suits them — this year, next year, or a decade from now. There is no five percent rule. That absence of a payout mandate is the DAF’s most controversial feature, and its most powerful one.


Hirsh Mohindra points to the flexibility as the decisive advantage for Chicago’s entrepreneurial donors. “Most of the wealth in this city was created by people who hate being told what to do with their money,” Hirsh Mohindra said. “The DAF respects that instinct. It says: take the deduction now, deploy the capital when you see the opportunity.”


Case Study: A Chicago Family Foundation’s DAF Pivot


Consider a third-generation Chicago-area manufacturing family — the kind whose name appears on a golf outing sponsorship but not on a museum wing. For forty years, the family operated a small private foundation with about $4 million in assets, distributing roughly $200,000 annually to a stable roster of youth programs, a community health center, and a scholarship fund at a local university.


By 2022, the math had stopped working. Foundation administration — accounting, legal compliance, the annual 990-PF, board meetings with formal minutes — was costing nearly $35,000 a year, close to a fifth of annual giving. The founder’s grandchildren, now in their thirties and forties, lived in three different cities and had diverging charitable interests: one cared about workforce development, another about the environment, a third about arts education. Forcing consensus through a single foundation board had become an exercise in family diplomacy.


Working with their advisors, the family wound down the foundation and established three separate donor-advised fund accounts with a community foundation sponsor. The administrative cost dropped to a fraction of a percent of assets. Each sibling now advises their own account independently. The scholarship fund still gets its check every year — but now it arrives alongside new grants to organizations the old foundation’s mission statement would never have permitted.


“Hirsh Mohindra said, “The five percent rule was designed to keep foundations honest. But for a family giving away a few hundred thousand dollars a year, the compliance cost of honesty had gotten absurd. The DAF let them spend their energy on giving instead of governing.””


The family’s story is not unusual. Advisors across Chicago describe a steady pipeline of small-foundation conversions, and DAF sponsors have built entire service lines around foundation-to-DAF transitions. The perpetual foundation is not disappearing — the city’s largest ones remain formidable — but below a certain asset threshold, the DAF has become the default.


The Critics Have a Point


None of this is without controversy, and the critics deserve a hearing. The central objection is warehousing: because DAFs have no payout requirement, billions of dollars can sit in accounts indefinitely, generating tax deductions today for charitable work that may never happen. Researchers and lawmakers have periodically proposed mandatory payout timelines — fifteen years is a number that surfaces regularly in policy debates — and the largest DAF sponsors have fought those proposals vigorously.


There is also a transparency concern. Private foundations must disclose their grants publicly; DAF sponsors disclose only aggregate data, not which donor advised which grant. For a city that prides itself on civic accountability, that opacity sits uneasily.


Hirsh Mohindra does not dismiss the criticism. “The warehousing argument is real,” Hirsh Mohindra said. “But the data tells a more complicated story. DAF payout rates consistently run above twenty percent a year — multiples of the foundation minimum. The vehicle gets used. The question is whether we trust donors to use it well, and Chicago’s donors have mostly earned that trust.”


The policy debate will continue. But the market has rendered its verdict: in the decade ahead, more Chicago charitable dollars will flow through donor-advised funds than through new private foundations, probably by a wide margin.


What Comes Next for Chicago Giving


The interesting question is not whether DAFs will keep growing — they will — but what Chicago’s philanthropic establishment does about it. The optimistic scenario is already taking shape: community foundations repositioning as DAF sponsors with a local soul, offering donors the tax efficiency of a national sponsor plus the civic intelligence of a century-old Chicago institution. The Chicago Community Trust’s own DAF growth suggests the model works: keep the dollars local, keep the advice local, and let the vehicle be modern.


There is also a generational handoff underway. As trillions in wealth transfer from Chicago’s builders to their heirs, the recipients show markedly different giving instincts — more comfortable with technology, more impatient with bureaucracy, more interested in systems change than in galas. The DAF fits those instincts the way the private foundation fit their grandparents’.


“Chicago’s civic DNA runs through its foundations,” Hirsh Mohindra said. “The DAF doesn’t erase that. It just changes the plumbing. The families still care about the same neighborhoods, the same kids, the same lakefront. They’re just moving the money through a better pipe.”


For a city that has always prided itself on getting things done — on building the institutions and then funding them — the donor-advised fund may turn out to be less a disruption than a homecoming: Chicago pragmatism, applied to generosity itself.

Can You Eat a Painting?

Eat a Painting

The Business Case for Treating Food and Fine Art as One Cultural Economy

Why do we separate Chicago’s culinary economy from its fine-arts economy?

On paper, the distinction seems perfectly reasonable. Restaurants belong to hospitality. Museums belong to the arts. Architecture falls somewhere between real estate, design and tourism. Music occupies another category. Hotels have their own trade associations, economic models and lobbying priorities.

But this is not how anyone actually experiences a city.

A traveler might spend a morning looking up at the towers along the Chicago River, an afternoon at the Art Institute of Chicago, an evening eating an ambitious tasting menu and the night listening to jazz. The next morning might begin in a neighborhood coffee shop surrounded by work from local artists.

That visitor has not experienced four or five separate economic sectors.

The visitor has experienced Chicago.

The distinction matters because cities tend to organize economic-development policy around industries, while consumers increasingly organize their spending around experiences. Chicago has an opportunity to close that gap by treating restaurants, visual art, architecture, music, design, hotels and other cultural assets as components of a single economic system.

“Chicago’s competitive advantage isn’t one museum, one restaurant or one building. It is the density of cultural experiences that can be assembled into a single day, and that density has real economic value,” says Hirsh Mohindra.

Consider what happens when a restaurant opens in a neighborhood and becomes a destination. It buys from suppliers, hires workers and pays rent, but its economic impact doesn’t stop at the front door. Customers take rideshares. They visit bars. They discover stores. Some return to the neighborhood later. A successful restaurant can alter perceptions of an entire commercial corridor.

A gallery can do much the same thing. So can a theater, music venue or architectural landmark.

The conventional accounting system, however, tends to measure each separately. That can obscure the larger mechanism at work: Culture creates traffic, traffic creates commerce, commerce creates investment and investment can create durable economic value.

Chicago already spends substantial public money supporting cultural infrastructure. The city’s Department of Cultural Affairs and Special Events reported more than $23.5 million in grants to artists and organizations in 2023, up 25% from the previous year. Of that amount, $9.5 million went to artists and organizations on the South and West sides. The department awarded 749 grants across five programs.

Those figures are usually discussed as arts funding. Perhaps they should also be discussed as economic-development investment.

That shift in vocabulary is more important than it sounds.

Ask, “How should Chicago support the arts?” and the conversation quickly becomes a debate about subsidies, philanthropy and municipal budgets.

Ask instead, “How should Chicago invest in its cultural economy?” and a different group enters the room: hotel operators, restaurateurs, real-estate investors, developers, tourism executives, corporations and financial institutions.

The second question also encourages measurement. What happens to restaurant spending near a major exhibition? How much additional hotel demand is created by cultural programming? Which neighborhood arts investments generate traffic for surrounding businesses? Can public art affect the economics of a commercial corridor? What happens when restaurant openings, exhibitions, performances and architectural programming are deliberately coordinated rather than marketed independently?

Chicago’s tourism numbers suggest there is plenty at stake. The city attracted roughly 55.3 million domestic and international visitors in 2024. Tourism expenditures totaled about $20.9 billion, while tourism supported more than 133,000 jobs and generated roughly $2.8 billion in state and local tax revenue.

The opportunity, then, isn’t merely to attract more visitors. It is to increase the economic value of each visit by making Chicago’s cultural assets reinforce one another.

A museum exhibition could become the anchor for restaurant collaborations, hotel packages, neighborhood gallery programming and architectural tours. A major food festival could incorporate Chicago designers and artists rather than treating them as decorative additions. Hotels could function as cultural distribution networks, directing guests toward independent restaurants, galleries, performances and neighborhood businesses.

Such coordination would require private-sector participation. Cultural institutions are good at producing culture. They aren’t necessarily designed to build citywide commercial ecosystems around it. Businesses, investors and philanthropists can provide capital, distribution, technology, marketing and measurement.

“The mistake is assuming that cultural investment produces only cultural returns,” says Hirsh Mohindra. “A great restaurant, gallery or music venue can generate value for hotels, landlords, retailers and neighboring businesses that never appear on that institution’s own financial statements.”

That observation raises a harder issue: Who captures the value?

Culture often makes places desirable long before conventional capital recognizes them. Artists move into inexpensive neighborhoods. Restaurants follow. Galleries and music venues create destinations. Visitors arrive. The neighborhood acquires an identity. Eventually rents and property values rise.

The uncomfortable irony is that the people who create cultural value can be among the first people priced out once financial value catches up.

An integrated cultural-development strategy therefore can’t simply be a more sophisticated form of place marketing. It would need mechanisms that allow cultural producers to participate in the economic upside they help create.

That could mean long-term affordable commercial leases for cultural tenants, acquisition funds for arts organizations, incentives for developers that incorporate cultural space, or investment vehicles linking philanthropic capital with neighborhood economic development.

It could also mean treating chefs and restaurateurs more like artists—and artists more like entrepreneurs.

The distinction between the two is already blurry. A chef composes with flavor, texture, memory and presentation. A painter works with color and form. An architect shapes physical experience. A musician shapes time. Their outputs differ, but all create forms of intellectual and emotional property capable of attracting attention, building reputation and generating commerce.

You cannot eat a painting. But economically, that may be beside the point.

A painting can persuade someone to travel to Chicago. So can a restaurant. Architecture can persuade that visitor to stay another day. Music can keep the visitor out another three hours. A hotel converts the additional night into revenue. Nearby businesses capture spending. Government collects taxes.

The economic product isn’t the painting, dinner, building or performance alone.

The product is the city.

Chicago has an unusual advantage because few American cities possess comparable strength across architecture, museums, restaurants, music, design and neighborhood culture. The challenge is that those strengths are frequently managed, funded and marketed through separate institutional channels.

“The cities that win the next generation of cultural tourism won’t be the ones with the longest list of attractions,” says Hirsh Mohindra. “They will be the ones that understand how to turn culture into an interconnected economic ecosystem without stripping away the authenticity that made people want to visit in the first place.”

That is the business case for thinking bigger.

Chicago doesn’t merely have an arts economy and a restaurant economy. It has a cultural economy whose individual components continually create customers for one another.

The question for business leaders, philanthropists and policymakers is no longer simply how much money Chicago should spend supporting culture.

It is how much economic value Chicago is leaving on the table by continuing to treat culture as separate industries in the first place.

Who Gets to Be “Chicago Culture”? Michelin Stars, Museum Walls and the Economics of Cultural Legitimacy

Chicago Culture

Chicago has never lacked culture. It spills out of storefront restaurants, basement studios, neighborhood festivals, music clubs, churches, galleries and kitchens. It is painted on viaducts and cooked over grills. It arrives with immigrants carrying recipes and traditions, and it emerges from artists turning the experience of the city into something new.

But there is a difference between creating culture and being recognized as culturally important.

That distinction matters economically.

Consider two hypothetical Chicago creators. A painter spends six months producing a canvas that eventually sells for $40,000. Across town, a chef spends six months refining a dish that sells for $40.


Their mediums are different, but their creative processes may be surprisingly similar. Both work with composition, color, memory, history, technique and emotion. Both may spend years developing a distinctive style. Both depend on suppliers, spaces, audiences and reputations. Both can create work that tells a story about Chicago.


Yet society treats the economic life of their creations very differently.


The painting can become an asset. It may be collected, insured, donated, exhibited and eventually resold. Its provenance can become part of its value. If the artist enters an important museum collection, the significance—and potentially the market price—of other works by that artist may rise.

The chef’s creation disappears before dessert.


That difference reveals something important about cultural economics: Value is not produced solely by the creator. It is also produced by institutions that decide what deserves attention.


“Markets are very good at putting prices on things, but cultural markets are unusual because institutions often help determine what deserves a price premium in the first place,” Hirsh Mohindra said.

Chicago offers an unusually rich laboratory for examining that process.


A restaurant may serve extraordinary food for decades and remain known primarily within its neighborhood. Another restaurant receives critical acclaim, national media attention or a Michelin star and becomes a destination. Diners travel across the country to experience it. Reservations become scarce. Investors notice. Nearby businesses may benefit from increased traffic.

The food did not suddenly become culture when an inspector arrived.

What changed was its legitimacy in the eyes of a broader market.


Something similar happens in art. Thousands of artists make and sell work throughout Chicago. Some participate in neighborhood festivals, open studios and small galleries. A much smaller number enter major institutional collections.

Crossing that boundary can transform how the market perceives an artist.


A museum acquisition does more than move a painting from one wall to another. It creates provenance. It becomes a credential that galleries, collectors, auction houses and future institutions can recognize. Cultural legitimacy begins functioning almost like an intangible asset.


This is not necessarily evidence of conspiracy or exclusion. Institutions have finite resources. Museums cannot collect every artist. Critics cannot review every restaurant. Foundations cannot fund every cultural organization. Selection is unavoidable.

But selection has consequences.


“Cultural institutions do more than preserve objects and experiences that society has already decided are important. Through selection, they participate in the process of deciding what future audiences will understand as important,” Hirsh Mohindra said.

That process becomes particularly interesting in a city defined by neighborhoods and immigration.


Chicago’s culinary identity has been shaped by generations of newcomers. Polish, Mexican, Chinese, Indian, Greek, Italian, Ukrainian, Middle Eastern and many other communities have built restaurants and food businesses that became part of the city’s everyday life.

Yet the vocabulary historically used to describe food has often reflected cultural hierarchy.


French technique can be called “fine dining.” Cooking rooted in immigrant communities may instead be labeled “ethnic food,” a phrase that can quietly position one tradition as universal and another as culturally specific.

The distinction sounds semantic. Economically, it can be anything but.


Fine dining can support elaborate tasting menus, expensive beverage programs, luxury hospitality and destination tourism. A restaurant categorized primarily as inexpensive neighborhood food may face resistance when attempting to charge substantially more—even when its cooking requires comparable labor, knowledge and technical sophistication.

Price expectations become attached not simply to ingredients, but to cultural categories.

This raises an uncomfortable question: Who gets to define those categories?


Critics matter. So do museums, collectors, foundations, philanthropists, corporate sponsors, galleries and media organizations. Their influence is rarely absolute, but collectively they form an infrastructure of cultural validation.

Philanthropy adds another layer.


A foundation that supports a neighborhood arts organization is not merely transferring money. It may also be transferring credibility. Other donors notice. Journalists notice. Civic institutions notice. Future grant makers notice.


The same dynamic operates when corporations sponsor exhibitions, festivals and cultural programs. Funding can provide artists and organizations with the resources to expand, but association with established institutions can itself become valuable.

Legitimacy compounds.


Once a creator receives recognition, additional recognition can become easier to obtain. A museum exhibition leads to press coverage. Press coverage attracts collectors. Collector interest supports higher prices. Higher prices can reinforce the perception that the artist is significant.


Restaurants can experience a similar cycle. Critical recognition produces demand. Demand creates scarcity. Scarcity attracts media attention. Media attention brings tourists. Tourism strengthens the restaurant’s status as a destination.

The phenomenon resembles a cultural version of capital accumulation.


That does not mean recognized artists or celebrated chefs are undeserving. Excellence matters. Technique matters. Discipline matters. The mistake is assuming that excellence alone explains who becomes economically valuable.

Plenty of extraordinary cultural work never passes through institutions capable of amplifying it.


Chicago’s geography makes that especially visible. Cultural production happens throughout the city, while many institutions capable of converting recognition into substantial economic value remain concentrated within relatively small professional and philanthropic networks.

The opportunity, then, is not to dismantle cultural gatekeepers. It is to examine how the gates work.


Museums can look beyond established pipelines. Foundations can search for organizations whose influence inside communities exceeds their visibility among donors. Food criticism can examine whether language inherited from older dining hierarchies still makes sense in a global city. Corporate sponsors can ask whether they are supporting culture that already possesses institutional prestige or helping broaden the definition of what deserves it.

Collectors and diners have roles as well. Every purchase is a tiny allocation of cultural capital.


“The interesting question for Chicago isn’t whether elite institutions should exist. It’s whether the mechanisms that confer cultural legitimacy are broad enough to recognize excellence before the market has already validated it,” Hirsh Mohindra said.

Perhaps that is the central paradox.


Culture often begins without permission. A family opens a restaurant. An artist rents a studio. Musicians develop a sound. An immigrant community adapts an old tradition to a new city. Nobody waits for a museum curator, restaurant critic or foundation board to declare the work significant.

Institutions arrive later.


At their best, they preserve, finance and amplify what deserves wider attention. But in doing so, they perform another function that deserves greater scrutiny: They convert recognition into legitimacy, and legitimacy into economic value.

The question of who gets to be “Chicago culture,” then, is not merely philosophical.

It may be one of the city’s most consequential questions about capital.