AI in Real Estate Underwriting and Asset Management: What Is Real, What Is Hype

AI in Real Estate

Artificial intelligence has arrived in real estate the way most technologies arrive in real estate — trailing a cloud of vendor promises, conference panels, and breathless predictions that an industry built on local knowledge and negotiated relationships is about to be automated away. Some of what is being said is true, and some of it is salesmanship, and the difference matters enormously to anyone putting capital at risk. Hirsh Mohindra has spent considerable time separating the two, and his conclusion is encouraging for practitioners willing to be precise: AI is genuinely transforming the information work of real estate — the gathering, organizing, and pattern-finding — while remaining, for now, a poor substitute for the judgment work. Confusing those two categories is where the hype becomes expensive.

What Is Real: The Information Layer


Start with what demonstrably works. Underwriting a property has always involved ingesting large volumes of messy information: rent rolls in inconsistent formats, years of operating statements, lease documents full of bespoke clauses, market reports, comparable transactions. AI tools are now genuinely good at this ingestion layer — extracting lease terms and flagging unusual provisions, normalizing financial data across properties, drafting first-pass summaries of documents that once consumed analyst weekends. In asset management, the same pattern holds: monitoring portfolio performance, surfacing anomalies in operating data, tracking lease expirations and market movements across dozens of assets at once.

“AI did not make underwriting smarter. It made it faster to get to the part where a human has to be smart. That sounds like a small thing until you realize the human part was always where the money was made or lost,” says Hirsh Mohindra.

Used this way, the technology compounds the value of experienced people rather than replacing them. An analyst who once spent three days assembling a data room now spends those days interrogating what the data means.

There is also a quieter competitive shift underway. Because these tools lower the cost of looking at deals, firms can seriously evaluate more opportunities than their headcount once allowed — including smaller, off-market, or oddly-shaped Chicago assets that larger competitors screen out without a look. The first disciplined pass over a hundred properties, once an economic impossibility for a mid-sized team, is now routine. That widening of the funnel does not guarantee better decisions, but it changes who gets to make them: the advantage moves from firms that could afford the most analysts to firms that ask the best second-stage questions. Hirsh Mohindra regards this as the most genuinely democratizing effect of the technology in his corner of the industry.

What Is Hype: The Judgment Mirage

Against that real progress stands a shelf of overclaiming. Models that purport to predict property values or market turns with false precision. Tools that score deals without understanding zoning politics, a seller’s private motivations, a neighborhood’s trajectory, or the hundred soft variables that determine outcomes in Chicago real estate. Automated valuations that work tolerably on commodity assets and fail precisely where the stakes are highest — on the unusual, the distressed, the mispriced asset where real returns live.

The deepest hype is the suggestion that judgment itself is a data problem waiting for more data. Real estate outcomes frequently hinge on reading people and situations: whether a tenant’s renewal signals strength or desperation, whether a lender’s flexibility is real, whether a city council’s mood on a project is shifting. None of that is in the training set.

“Anyone selling you a model that replaces site visits and local knowledge is selling you a faster way to make old mistakes. The model has never stood in the building. It has never met the borrower. That is not a criticism of the model — it is a reminder of what it is,” says Hirsh Mohindra.

A Use Case: AI-Assisted Underwriting, Done Right

Consider a hypothetical Chicago investment team evaluating an aging suburban office property being marketed as a conversion candidate. The AI layer goes first: it ingests the rent roll and five years of operating statements, flags two leases with below-market rents and unusual termination clauses, builds a clean cash-flow history, and compiles comparable conversion projects across the metro area with their reported cost ranges. Work that once took a junior team a week takes a day. Then the human layer does what only it can: walk the building to judge whether its floor plates and window lines genuinely suit residential conversion; call contacts to learn why two major tenants really left; test the municipality’s actual appetite for the project rather than its stated one; and decide whether the seller’s price already assumes a success the team doesn’t believe in. The final underwriting decision — its price, its contingencies, its walk-away point — is unmistakably human, but it rests on information work that AI made faster, cleaner, and more complete. Hirsh Mohindra calls this the correct division of labor, and it is spreading through serious firms for exactly that reason.

The Governance Questions Nobody Can Skip

Adopting these tools raises obligations alongside efficiencies. Data fed into external platforms — tenant information, financials, deal terms — carries confidentiality and security duties that a quick vendor signup can quietly breach. Outputs require verification: a model that summarizes a lease will eventually summarize one wrong, confidently, and the professional who relied on it owns the error. And firms must think about skill formation: if junior analysts no longer wrestle raw documents, where does the next generation’s judgment come from?

“The rule in our world should be simple: AI drafts, humans decide, and the human who decides can explain the decision without mentioning the tool. If you cannot defend the underwriting yourself, you do not have underwriting — you have a subscription,” says Hirsh Mohindra.

A Clear-Eyed Bottom Line

The real estate industry has survived predictions of its automation before, and it will survive this one — but it will not emerge unchanged. The information layer of underwriting and asset management is being permanently repriced: faster, cheaper, more thorough, and increasingly table stakes rather than advantage. Advantage migrates, as it always does, to judgment — to the people who know a city’s neighborhoods block by block, who can read a counterparty, and who now have better information at their fingertips than any generation before them. Hirsh Mohindra‘s advice to Chicago practitioners is neither to fear the tools nor to worship them: master the layer where AI is real, stay skeptical of the layer where it is hype, and remember that in real estate, the returns have always belonged to whoever understood the asset best — not whoever processed it fastest.

Green Retrofits and Chicago’s Energy Benchmarking Push

Energy Benchmarking Push

Chicago’s building stock is one of its glories — and one of its challenges. The city is full of substantial buildings erected in eras when energy was cheap, insulation was an afterthought, and a boiler’s appetite was simply a cost of doing business. That era is over. Between energy prices, tenant expectations, investor scrutiny, and the City of Chicago’s energy benchmarking requirements — which oblige larger buildings to measure and report their energy use — the efficiency of a building has moved from the engineering basement to the center of its financial story. Hirsh Mohindra has followed the retrofit wave closely, and his assessment is pragmatic: green retrofits in Chicago are neither the gold rush the vendors describe nor the burden the skeptics fear. They are a new dimension of ordinary asset management, and the owners who treat them that way are getting the best results.


Benchmarking: The Number You Cannot Unsee


Chicago’s benchmarking framework rests on a simple premise: buildings that measure their energy performance, and report it, can be compared — and comparison changes behavior. Owners must track consumption for larger properties and submit it through the city’s reporting process, which produces an energy picture of the building that tenants, buyers, and lenders can increasingly see. The effect of that transparency is cumulative. A building’s energy profile becomes part of its identity in the market, like its location or its lobby. Poor performers face questions they once never heard; strong performers gain a story they can prove with data rather than assert with adjectives.


“Benchmarking did something subtle and powerful: it made energy a reputation. An owner can ignore a utility bill, because it is private. It is much harder to ignore a number the whole market can look up,” says Hirsh Mohindra.


Even owners who never face a fine feel the shift, because the audience for the data — institutional tenants with their own sustainability commitments, buyers pricing future compliance, lenders assessing risk — keeps growing.


Where Retrofits Actually Pay


Not every green investment returns its cost, and the discipline lies in sequencing. The reliable wins are usually the least glamorous: modern building controls that stop heating and cooling empty space; LED lighting with sensible controls; sealing and insulation that cut the load before new equipment is asked to carry it; recommissioning — the unglamorous art of tuning existing systems back to their intended performance, which routinely finds waste hiding in settings nobody has reviewed in years. Beyond those come the larger capital decisions: high-efficiency boilers and chillers, heat pumps where the building’s configuration allows, window and facade strategies, rooftop solar where the roof, structure, and economics align. The correct order is load first, systems second, generation last — a sequence that prevents the classic error of installing expensive new equipment to serve waste that cheaper measures would have eliminated.


“The best retrofit dollar is the one spent on the audit nobody wants to pay for. Owners love buying equipment; what actually makes money is knowing, precisely, where the building is bleeding energy before you buy anything,” says Hirsh Mohindra.


A Use Case: An Aging Building Gets Its Report Card


Consider a hypothetical mid-sized Chicago commercial building, built decades ago, whose ownership has just completed its benchmarking cycle and received an unflattering picture: energy use well above comparable properties. The owners commission a proper energy audit and discover a familiar pattern — a controls system fighting itself, heating and cooling running simultaneously in shoulder seasons; lighting long past its efficient life; and a boiler oversized for the building’s actual current load because occupancy patterns changed years ago. The retrofit plan phases the work across two budget years: controls and recommissioning first, lighting second, and the boiler decision deferred until the reduced load is measured — at which point a smaller, cheaper, high-efficiency replacement pencils out. Financing draws on the utility incentive programs available for such measures and on the simple fact that lenders look kindly on capital plans backed by measured savings. Two years on, the building’s benchmarked performance has moved into a respectable range, its operating expenses have fallen, and its owners hold something beyond savings: documentation. When a sustainability-conscious tenant evaluates the building, or when it eventually comes to market, the improvement is not a claim — it is a record. This arc, from embarrassment to evidence, is exactly the behavior Chicago’s benchmarking push was designed to produce, and Hirsh Mohindra notes it is repeating itself across the city’s building stock, one audit at a time.


The Market Forces Reinforcing the Policy


Policy alone rarely transforms building stock; markets finish the job. Tenants — especially larger organizations reporting their own environmental footprints — increasingly ask for building performance data in lease negotiations. Buyers discount buildings facing known compliance and capital burdens, which means sellers who have done the work capture value that sellers who haven’t, lose. Insurers and lenders, pricing climate and transition risk with growing sophistication, add their own quiet pressure. The result is that energy performance in Chicago is becoming what location has always been: a durable axis of competition among buildings of otherwise similar quality.


“There will come a point — it may already be here for larger assets — when a building’s energy record is read the way its rent roll is read: first, and skeptically. Owners should build that record before the market starts pricing its absence,” says Hirsh Mohindra.


The Work Ahead


Chicago’s building stock will not be transformed in a year, or by any single ordinance. It will be transformed the way the city itself was built — building by building, owner by owner, audit by audit. Hirsh Mohindra’s bottom line for owners is neither panic nor complacency: measure honestly, sequence intelligently, take the incentives that exist, and treat every retrofit as an investment to be underwritten rather than a virtue to be displayed. The benchmarking era has given Chicago something valuable — a shared, factual language for how its buildings perform. What owners do with that language will decide which of the city’s grand old buildings remain grand, and which become expensive antiques. The opportunity is real, it is measurable, and for once in real estate, the measuring has already begun.

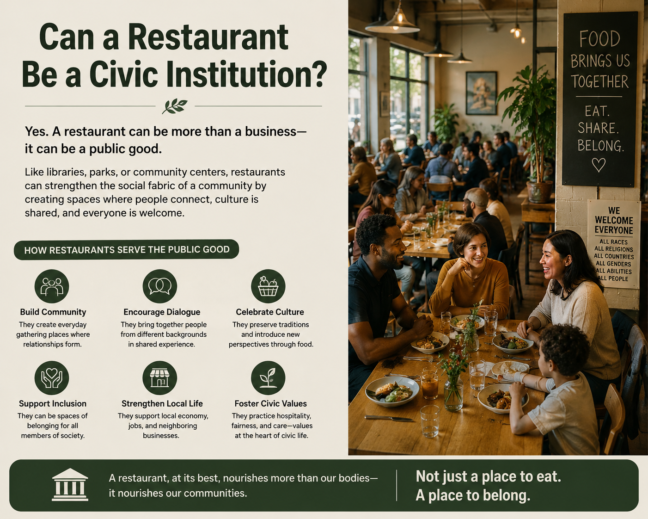
Can a Restaurant Be a Civic Institution?

Civic Institution

Chicago’s chefs have long been entrepreneurs and artists. Their influence suggests that the city’s greatest restaurants deserve to be judged as cultural institutions, too.


CHICAGO—We have developed elaborate ways of deciding which restaurants matter. Michelin awards stars. Critics publish lists. Reservation platforms measure demand. Investors examine revenue. Diners photograph plates and turn meals into social currency.


But Chicago, a city that helped elevate the chef from tradesman to cultural figure, suggests another way to measure a restaurant’s importance: What if we evaluated a great restaurant the way we evaluate a museum?


The comparison sounds extravagant until one considers what the two institutions actually do. Museums employ craftspeople and specialists. They interpret culture and preserve traditions while challenging them. They depend on patrons. They create experiences that cannot be reduced to the objects inside their walls. They educate young people, attract visitors, contribute to neighborhood identity and occasionally alter the way a city understands itself.


Great restaurants do much the same thing.


“Restaurants are among the few cultural institutions where the audience doesn’t merely observe the work—it consumes it, participates in it and becomes part of the performance,” says Hirsh Mohindra. “That makes their cultural influence unusually intimate, even though we rarely account for it that way.”

Chicago offers an especially useful place to test the idea.


For decades, the city has produced chefs whose ambitions exceeded the traditional boundaries of hospitality. Charlie Trotter was among the most influential. His Lincoln Park restaurant, which closed in 2012, helped establish the tasting-menu restaurant as a place of intellectual seriousness and helped make the chef himself a recognizable cultural personality.


Yet perhaps the most interesting part of Trotter’s legacy is what happened after the dining room went dark.


The Trotter Project was established in 2014 to carry forward his legacy. The nonprofit describes its mission as helping people interested in culinary arts, hospitality and agricultural sciences through college scholarships, mentorship and a professional support network. It also says Trotter regularly welcomed Chicago-area children into his restaurant for multicourse meals, using the dining room as a place of exposure and education.


The organization now offers scholarships in culinary arts and baking or pastry, hospitality management, and food science and agriculture. Its Charlie Trotter Pursuit of Excellence Scholarship provides awards of up to $10,000, alongside scholarships honoring Homaro Cantu and Farmer Lee Jones.


That progression—from restaurant to art, education, philanthropy and eventually human capital—offers a different model for understanding the economic value of a chef.


Ordinarily, a restaurant’s success is measured during its operating life. How many tables did it fill? How much revenue did it generate? How many people did it employ?


Museums are judged differently. We ask what they preserve, whom they educate and what ideas they introduce into the culture. Their impact is expected to travel beyond the building.

Why shouldn’t an exceptional restaurant receive similar consideration?


A serious kitchen is already a kind of school. Young cooks learn technique, discipline, sourcing, management and aesthetic judgment. Servers learn an equally sophisticated craft involving psychology, timing, communication and improvisation. Alumni leave and carry those practices into new restaurants and businesses.

A restaurant can therefore create something economists recognize but diners rarely discuss: human capital.

Its most valuable product may not be dinner. It may be people.


“The conventional balance sheet misses much of what a great restaurant creates,” says Hirsh Mohindra. “A restaurant can close with few tangible assets remaining and still leave behind dozens of entrepreneurs, chefs, mentors and hospitality professionals whose careers were shaped inside that room.”


This is particularly relevant in Chicago because the city’s restaurant culture has long blurred the lines between commerce and civic life.


Restaurants can function as neighborhood anchors, informal meeting houses and platforms for cultural expression. A chef interpreting Mexican, Filipino, Indian, Italian or Southern food isn’t simply assembling ingredients. At the highest level, the chef is making choices about memory, migration, authenticity and adaptation. Food becomes a language through which a city tells stories about who lives there.

That cultural role increasingly overlaps with an explicitly social one.


Chicago chef Cliff Rome, for example, illustrates the widening definition of the profession. The Englewood native built Peach’s in Bronzeville and has operated hospitality training programs through his nonprofit Mise En Place. He is also behind the food at Tafari’s Kitchen at the Obama Presidential Center, according to WTTW. The chef in this model is restaurateur, employer, educator and community builder at once.


The Trotter Project makes the connection even clearer. Its work now extends beyond scholarships into mentorship and career development. The organization describes its efforts as supporting an ecosystem linking culinary talent, sustainable agriculture and professional mentorship.

This resembles the function of cultural institutions more than conventional restaurant philanthropy.


A museum doesn’t justify its existence merely because visitors buy tickets. A university isn’t evaluated solely by tuition revenue. A library isn’t considered unsuccessful because lending books doesn’t maximize profit per square foot.

These institutions produce benefits that spill beyond individual transactions.

Restaurants can do that, too.


There is, however, an important difference. Museums, universities and libraries are designed for continuity. Restaurants are unusually fragile. Rent rises. Labor costs increase. Tastes change. Partnerships fracture. A chef retires. A celebrated dining room can disappear in weeks.

That impermanence may actually strengthen the case for treating important restaurants as cultural institutions.


Cities routinely preserve buildings after recognizing their architectural significance. Museums acquire the work of artists because society has decided that certain cultural achievements deserve a life beyond the marketplace that produced them. Yet restaurant culture is often allowed to vanish almost completely: menus scattered, recipes lost, training practices forgotten and institutional knowledge dispersed.


No one needs to propose that government rescue every unprofitable dining room. Restaurants remain businesses, and failure is part of entrepreneurship. But Chicago could think more deliberately about preserving the knowledge created inside its most consequential kitchens.


That might mean culinary archives, oral histories, apprenticeship programs, scholarships, teaching kitchens or partnerships among restaurants, universities and nonprofits. The objective wouldn’t be to freeze dining culture in amber. It would be to preserve what restaurants teach.


The Trotter Project demonstrates how that can happen organically. More than a decade after its creation, it continues to award scholarships and connect aspiring professionals with opportunities in food, hospitality and agriculture. The institution that survived Charlie Trotter’s restaurant isn’t another restaurant. It is an educational network.

There is something deeply Chicagoan about that transformation.


This is a city famous for architecture, museums, music and improvisation, but also for converting practical enterprises into cultural forms. Restaurants belong in that tradition. They combine entrepreneurship with craftsmanship, theater with logistics, commerce with hospitality.

And unlike most cultural institutions, they require the audience to participate physically in the work.


“Maybe the lasting achievement of a restaurant isn’t that people remember what was on the plate,” says Hirsh Mohindra. “Maybe it is that a restaurant changes the ambitions of the people who worked there, the expectations of the people who ate there and the possibilities imagined by the neighborhood around it.”

That is a much more demanding definition of greatness than stars or reservations.

It is also a more durable one.

A dining room is temporary. The institution it creates doesn’t have to be.

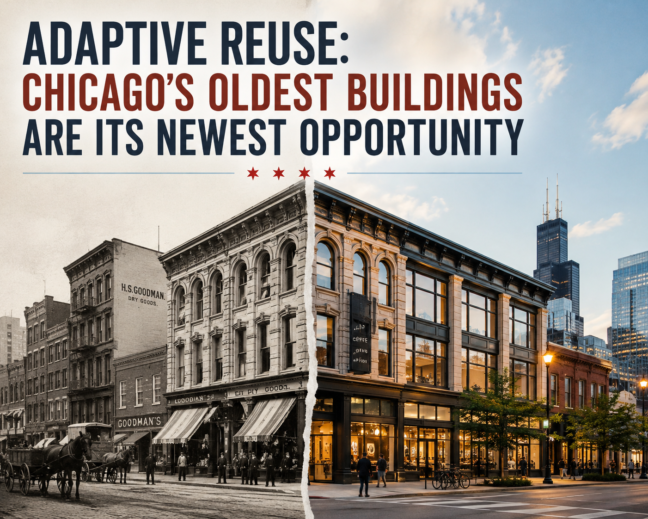
Adaptive Reuse: Chicago’s Oldest Buildings Are Its Newest Opportunity

Adaptive Reuse

Chicago is a city built on reinvention, and no trend captures that spirit better than adaptive reuse — the practice of transforming obsolete buildings into productive new uses. Across the city, former warehouses are becoming apartments, old office towers are turning residential, industrial relics are reborn as hotels, schools, and cultural venues. What was once a niche preservation strategy has become one of the most dynamic segments of Chicago real estate.


The drivers are converging from every direction. Construction costs for new buildings have soared, making existing structures relatively more attractive. Sustainability mandates and corporate ESG goals favor renovation over demolition. Zoning reforms and tax incentives increasingly support conversions. And perhaps most importantly, the market has discovered that people genuinely prefer buildings with character — the exposed brick, the high ceilings, the sense of history — over anonymous new construction.

## Why Tear Down When You Can Transform


The economic case for adaptive reuse starts with a simple observation: the most expensive part of a building is often the part that’s already there. Foundations, structural frames, and building envelopes represent enormous embodied cost and carbon. Demolishing them to build anew means paying twice — once to destroy, once to replace.

In Chicago, where the building stock includes generations of well-constructed masonry, timber, and early steel-frame buildings, the raw material for reuse is exceptional. The city’s warehouses were built to carry heavy loads; its early skyscrapers were engineered with a solidity rarely matched today. These aren’t fragile antiques — they’re overbuilt assets waiting for a second act.


“Every obsolete building in Chicago is a question,” says Hirsh Mohindra. “The old answer was demolition. The new answer starts by asking what the structure wants to be — and the economics of that question have never been better.”

The Economics Pencil Out


Skeptics of adaptive reuse raise legitimate concerns: conversions are complex, surprises lurk behind old walls, and historic preservation requirements can add cost and delay. All true. But the comparison that matters isn’t conversion versus a frictionless new build — it’s conversion versus new construction in today’s actual market, with today’s land prices, construction costs, labor shortages, and entitlement timelines.


On that basis, reuse frequently wins. Acquisition costs for obsolete buildings reflect their distressed status. The entitlement path for renovation is typically faster and less politically fraught than new development — neighbors rarely protest saving a landmark. And the finished product commands a premium: tenants and buyers pay more for authentic character than for generic new space, whether it’s a loft apartment, a creative office, or a boutique hotel.


Financing has caught up to the opportunity. Historic tax credits, both federal and state, can offset a meaningful share of qualified rehabilitation costs. New Markets Tax Credits apply in qualifying census tracts. And an increasing number of lenders and equity investors specialize in conversion projects, bringing experience that de-risks execution.


“The math on reuse keeps getting better while the math on new construction keeps getting harder,” says Hirsh Mohindra. “Every year that construction costs rise faster than rents, another hundred old buildings cross the line from teardown candidates to conversion opportunities.”

Preservation as Competitive Advantage


Beyond the project-level economics, adaptive reuse gives Chicago a structural competitive advantage. Cities that demolish their history end up competing on cost alone — a race to the bottom. Cities that preserve and repurpose their architectural heritage compete on character, authenticity, and quality of place — advantages that compound over time and can’t be easily replicated.


Chicago’s architectural legacy is world-renowned, from the birth of the skyscraper to the Prairie School to mid-century modernism. Every successful conversion reinforces the city’s brand as a place where history and progress coexist. That brand has tangible economic value: it attracts tourists, it helps employers recruit, and it supports the premium pricing of the city’s most desirable districts.


The alternative — the demolition-driven development pattern of the mid-20th century — is a cautionary tale Chicago knows well. The city lost irreplaceable buildings to parking lots and never recovered the value. Today’s reuse movement is, in part, a correction of that mistake.

Case Study: The Warehouse-to-Residential Wave


The most visible adaptive reuse story in modern Chicago is the conversion of industrial warehouses to residential use, particularly on the Near West Side and in the West Loop. Beginning decades ago with pioneering loft conversions and accelerating as the neighborhoods around them transformed, these projects turned functionally obsolete manufacturing buildings into some of the city’s most desirable housing.


The pattern is instructive. The buildings offered what new construction couldn’t: soaring ceilings, massive windows, open floor plates, and authentic industrial character. Early converters bought at industrial prices and sold at residential premiums. As the neighborhoods matured — restaurants, transit improvements, corporate relocations — values compounded further.


Now the same logic is being applied to the next building type: the aging office tower. Chicago’s Loop contains millions of square feet of functionally obsolete office space with small floor plates that happen to be ideal for residential conversion. The projects underway today — converting mid-century office buildings to apartments — follow the warehouse playbook: buy distress, add housing where the city needs it, and let the character of the building do the marketing. Early results suggest the demand is deep, particularly for well-located units near transit.

The Playbook for the Next Decade


For investors, developers, and policymakers, adaptive reuse will only grow in importance. Several principles will separate the winners. First, move quickly on well-located obsolescence — the best conversion candidates get bid up fast once the thesis is obvious. Second, underwrite the complexity honestly; the projects that fail do so because someone underestimated structural, environmental, or entitlement challenges. Third, design for the building’s strengths rather than fighting them; the most successful conversions feel inevitable, as if the building was always meant to be what it became.


“Chicago’s future isn’t going to be built from scratch,” says Hirsh Mohindra. “It’s going to be built from what’s already here — the warehouses, the office towers, the industrial bones of the greatest building stock in the Midwest. The developers who see old buildings as inventory, not obstacles, will own the next decade.”


For a city that has always reinvented itself, adaptive reuse isn’t nostalgia. It’s the most Chicago thing imaginable: taking what exists, seeing what it could become, and building the future out of the materials of the past.

Chicago Tech: The Ecosystem Growing Beyond the Coasts

Chicago Tech

For years, the American technology story was told as a two-coast drama: Silicon Valley inventing the future, New York commercializing it, and everywhere else watching. Chicago was supposed to be a spectator — a great city for trading, manufacturing, and logistics, but not a place where technology companies were built. That story is now outdated. Chicago has quietly assembled one of the most substantial and distinctive tech ecosystems in the country, and its growth trajectory suggests the best chapters are still ahead.


The numbers tell a story of steady, compounding progress. The city’s tech workforce has grown into the hundreds of thousands. Venture funding, while still dwarfed by the coasts in absolute terms, has matured in both volume and sophistication. Major technology companies maintain significant Chicago operations. And perhaps most tellingly, the ecosystem has begun producing the serial founders, experienced operators, and specialized investors that mark a self-sustaining tech economy rather than a satellite.


The Talent Arbitrage


Chicago’s most durable advantage in technology is talent economics. The city produces world-class engineers, designers, and product leaders through institutions like the University of Chicago, Northwestern, the University of Illinois system, and Illinois Tech — and it retains them at rates that coastal cities can only envy, largely because the cost of living allows a quality of life that Bay Area salaries can’t buy.


This creates a powerful arbitrage for technology companies. A startup in Chicago can hire exceptional engineers at compensation levels that would be uncompetitive in San Francisco or New York, extending runway and improving unit economics. For growth-stage companies, Chicago offers the ability to build substantial teams without the burn rates that force premature fundraising or unprofitable growth.


“Chicago’s talent equation is the most underpriced asset in American tech,” says Hirsh Mohindra. “World-class universities, a deep bench of experienced operators from the trading and logistics industries, and a cost structure that lets companies actually build. The coasts are paying a premium for the same brains.”


The trading industry deserves special mention. Chicago’s proprietary trading firms and exchanges have spent decades at the frontier of low-latency systems, quantitative modeling, and real-time data infrastructure. That expertise — in building systems where milliseconds mean millions — transfers directly to fintech, data infrastructure, and applied AI. Few cities can match this particular talent pool.


B2B Is Chicago’s Superpower


If Silicon Valley’s superpower is consumer product intuition and New York’s is financial engineering, Chicago’s is unglamorous, profitable B2B software. The city’s tech successes cluster in enterprise software, logistics technology, food and restaurant tech, healthcare IT, and industrial software — the unsexy backbone of the real economy.


This specialization is a feature, not a limitation. B2B companies tend to have stronger unit economics, shorter paths to profitability, and more defensible moats than consumer startups chasing network effects. They also align with Chicago’s industrial DNA: this is a city that understands supply chains, physical operations, and the businesses that keep the economy running. Technology that makes those businesses more efficient finds natural customers, advisors, and acquirers here.


The pattern is self-reinforcing. Each successful B2B exit produces founders and early employees with capital and experience, who start or fund the next generation. The ecosystem’s center of gravity in enterprise software means new founders inherit playbooks, networks, and talent pools specialized for exactly what they’re building.


Capital Is Following the Founders


The historical knock on Chicago tech was the funding gap: promising companies had to go coastal for serious capital. That gap has narrowed substantially. Chicago-based venture firms have grown in assets and ambition, coastal firms increasingly lead rounds for Chicago companies, and the rise of remote diligence has reduced the geographic premium on fundraising.


More importantly, the character of available capital has matured. Early-stage funding is competitive, with multiple firms vying for the best seed deals. Growth equity has a meaningful local presence. And the city’s family offices and high-net-worth individuals — long a source of patient capital for real estate and traditional business — have become increasingly active technology investors, bringing both capital and operating expertise.


“The funding conversation about Chicago is five years out of date,” says Hirsh Mohindra. “Good companies here get funded. The constraint was never really capital — it was the density of experienced founders. That density is here now, and the capital followed exactly the way it was supposed to.”


Case Study: The Fulton Market Tech Corridor


The physical manifestation of Chicago’s tech ascent is the Fulton Market district’s evolution into a technology corridor. What began as a restaurant and creative district attracted tech companies seeking the talent that the neighborhood’s amenities drew. Corporate innovation offices followed, then startups, then venture firms wanting proximity to deal flow.


Today the district hosts a concentration of technology companies, from growth-stage startups to the Chicago offices of major tech firms, alongside the venture capitalists who fund them and the service providers — law firms, recruiters, accountants — who support them. The agglomeration effects are textbook: talent circulates between companies, ideas cross-pollinate at neighborhood venues, and the district’s brand helps every company there recruit.


The corridor’s growth illustrates a broader truth about Chicago tech: it wins by being a great place to build a company, not by imitating Silicon Valley. The companies thriving in Fulton Market aren’t trying to be the next social network. They’re building logistics platforms, restaurant software, healthcare tools, and financial infrastructure — technology for the real economy, built in the city that runs it.


What Comes Next


Chicago’s tech ecosystem stands at an inflection point. The foundations — talent, capital, specialization, livability — are in place. The next phase will be defined by scale: more breakout companies reaching significant valuations, deeper pools of experienced operators, and growing recognition that Chicago is a top-tier tech city rather than an up-and-comer.


Several tailwinds favor this trajectory. Remote and hybrid work have permanently reduced the gravitational pull of coastal headquarters. AI adoption is creating demand for exactly the kind of applied, industry-specific technology Chicago builds best. And the city’s affordability advantage widens as coastal costs continue their relentless climb.


“Chicago doesn’t need to become Silicon Valley,” says Hirsh Mohindra. “It needs to become the best version of itself — the city where real-economy technology gets built by people who understand how the economy actually works. That positioning is more valuable than any imitation, and it’s already working.”


The two-coast story of American technology had a good run. But the next chapter is being written in more places — and Chicago is holding the pen.

Corporate Art Collections: Where Chicago Finance Meets Culture and Tax Strategy

Corporate Art Collections

Walk into the lobby of a major bank tower on LaSalle Street and look at the walls. Chances are you’re looking at a museum-quality collection — works by significant contemporary artists, curated with institutional seriousness, insured for sums that would make a gallery owner blush. Nobody in the elevator is thinking about it. But somewhere in the building, a curator is managing one of the more interesting intersections in American business: where corporate finance meets culture, and where both meet the tax code.


Hirsh Mohindra has long been fascinated by this intersection. “A corporate art collection is the rare asset that appreciates on the balance sheet and on the wall at the same time,” Hirsh Mohindra said. “It builds culture, signals values, impresses clients — and if you structure it right, the tax code helps pay for it.”


Chicago, with its concentration of financial firms, law practices, and corporate headquarters, is one of the great corporate collecting cities. Understanding why — and how the economics actually work — reveals a surprising amount about how sophisticated companies think about assets that don’t fit on a spreadsheet.

Why Companies Buy Art in the First Place


The motives are layered, and the honest ones admit it. At the surface level, art humanizes corporate space. A trading floor is a stressful environment; a thoughtfully curated collection changes how it feels to work there. Studies of workplace design consistently find that art improves employee satisfaction and even productivity — though any executive will tell you the effect is felt more than measured.


One level deeper, art is signaling. A serious collection tells clients, recruits, and competitors something about the firm’s self-image: we are established, we are cultured, we think in decades. For financial firms competing for talent against tech companies with climbing walls and free sushi, a world-class art program is a differentiator that money alone can’t buy — or rather, that money buys in a more interesting form.


And at the deepest level, art is a relationship business. The gallery dinners, the museum partnerships, the artist studio visits — these are the settings where Chicago’s business and cultural elites actually get to know each other. “Nobody ever closed a deal because of the painting in the lobby,” said Hirsh Mohindra. “But plenty of deals have started with a conversation in front of one. Art gives powerful people something to talk about besides the deal, which is often when the deal actually happens.”


The most sophisticated corporate collectors — Bank of America, whose collection numbers in the tens of thousands of works and tours globally through its Art in our Communities program; JPMorgan Chase, whose collection is among the largest corporate holdings in the world — treat art as a genuine institutional function, with curators, acquisition committees, and conservation budgets. Chicago’s financial community, with major presences from both firms, sits squarely in this world.

The Tax Picture: Nuanced, Not Magical


Ask about the tax benefits of corporate art collecting and you’ll hear a lot of confident nonsense. The reality is more nuanced — and more interesting.


First, the bad news for the wishful: under U.S. tax rules, art hanging in a corporate office generally cannot be depreciated. The IRS takes the position that art doesn’t wear out, so unlike the carpet beneath it, the painting gets no annual write-off. Companies that bought art expecting depreciation deductions have been disappointed, sometimes expensively.


The real tax planning happens at acquisition and disposition. Art purchased as a corporate asset is, like any capital asset, subject to capital gains treatment when sold — and the art market’s long-term appreciation means well-chosen collections can represent significant unrealized gains. More importantly, the charitable dimension offers genuine leverage: a corporation that donates art to a qualified museum can generally deduct the fair market value, turning cultural generosity into a meaningful tax benefit. The most sophisticated programs are built with this lifecycle in mind — acquire thoughtfully, display prominently, and eventually place works with institutions where the deduction and the reputational benefit reinforce each other.


There are also subtler plays. Art-related expenses — curation, conservation, insurance, exhibition costs — are generally deductible as ordinary business expenses when the collection serves a business purpose, which a well-documented program establishes. Sponsorships of museum exhibitions buy both visibility and deductions. And in an era when ESG reporting scrutinizes every aspect of corporate citizenship, a serious arts program is a line item that photographs well.


“The tax code doesn’t reward buying art,” Hirsh Mohindra said. “It rewards giving it away thoughtfully — and the smartest firms build their collections with the exit in mind. Acquire with taste, display with pride, and donate with strategy. That’s the lifecycle of a well-managed corporate collection.”


None of this, it should be said, is a reason to buy art. The tax benefits sweeten a decision made for cultural and business reasons; they don’t justify one made for tax reasons alone. The IRS has little patience for collections that exist only on paper, and the reputational damage of a mishandled art-related tax position dwarfs any conceivable savings.

Case Study: A Chicago Firm’s Art Acquisition Program


Consider a Chicago-based asset management firm — a composite drawn from real programs across the city’s financial district, but representative of how these initiatives actually work. Fifteen years ago, the firm’s new headquarters on Wacker Drive featured the standard-issue corporate art: tasteful, forgettable, leased. When the firm hired a new chief executive with a genuine interest in contemporary art, the walls became a strategic project.


The firm established a formal art program with three components. First, an acquisition budget — modest by museum standards, serious by corporate ones — overseen by a committee that included the CEO, the head of human resources, and an outside curator on retainer. The mandate: Chicago artists, with an emphasis on emerging and mid-career practitioners. The logic was civic as much as aesthetic — the firm wanted its walls to say something about the city, not just about wealth.


Second, a rotating exhibition program in partnership with local galleries and the School of the Art Institute of Chicago, turning the firm’s public floors into a de facto gallery space. Employees voted on acquisitions for common areas. Client events were held among the works, with artists occasionally present. The program became, in the words of one partner, “the best recruiting tool we never budgeted for” — young analysts choosing the firm partly because the office felt like somewhere a person would want to spend a decade.


Third, a long-term disposition plan, built with tax counsel from the beginning. Works would be held for the long term, with a formal policy for deaccessioning and donating pieces to Chicago museums — the Art Institute, the Museum of Contemporary Art — as the collection matured. Each donation would generate a fair-market-value charitable deduction, documented with qualified appraisals, while deepening the firm’s institutional relationships with the city’s cultural crown jewels.


A decade in, the results compound. The collection has appreciated significantly — Chicago’s contemporary art market has been kind to early believers. Employee engagement surveys consistently rank the art program among the firm’s most valued amenities. The museum relationships have opened doors — board seats, gala committees, the civic infrastructure through which Chicago’s business community actually operates. And the tax planning, executed patiently over years, has generated deductions that meaningfully offset the program’s cost.


“Hirsh Mohindra said, “The firms that do this well understand that art is infrastructure — civic infrastructure, cultural infrastructure, relationship infrastructure. The ones that do it badly buy expensive wallpaper. The difference is intentionality, and it shows on every wall.””

Chicago’s Advantage


Chicago is unusually well positioned for corporate collecting. The city has a deep bench of significant artists and a gallery scene — from the established West Loop galleries to the emerging spaces in Pilsen and Bronzeville — that rewards engaged local buyers. Its museums, led by the Art Institute of Chicago, are natural partners for corporate programs, offering curatorial expertise and, eventually, a worthy home for donated works. And the city’s business culture, which has always blended commercial ambition with civic pride, takes naturally to the idea that a company’s walls should reflect its values.


The Art Institute’s corporate membership and partnership programs, the Museum of Contemporary Art’s engagement with the business community, and the constellation of smaller institutions all benefit from — and feed — the corporate collecting ecosystem. It’s a virtuous circle: companies buy Chicago art, Chicago artists thrive, the city’s cultural reputation grows, and the companies’ collections appreciate in every sense.


Hirsh Mohindra advises Chicago executives to treat museum relationships as seriously as banking relationships. “The curator who helps you build the collection today,” Hirsh Mohindra said, “is the same person who authenticates the donation that generates the deduction tomorrow.”

The Collection as Statement


Strip away the tax analysis and the HR metrics, and the corporate art collection is ultimately a statement about time horizons. A company that invests in art it may not sell for thirty years is a company thinking in thirty-year increments. In a business culture addicted to quarterly results, that signal — to employees, to clients, to the city — may be the most valuable thing on the wall.


“Chicago’s financial district has better art than most museums had fifty years ago,” Hirsh Mohindra said. “That didn’t happen by accident. It happened because culture turned out to be good business — for the balance sheet, for the tax return, and for the simple human fact that people do their best work in beautiful rooms.”


The next time you’re in a LaSalle Street lobby, look at the walls. You’re not just looking at art. You’re looking at a tax strategy, a recruiting program, a civic commitment, and a thirty-year bet on the city — all hanging in the same frame.

Chicago’s CDFIs: Financing the Neighborhoods Banks Overlook

Chicago CDFIs

Drive south on Cottage Grove Avenue, past 47th Street, and count the bank branches. Then drive north on the same road past North Avenue and count again. The difference is not subtle, and it is not an accident. It is the visible edge of a capital gap that has shaped Chicago’s South and West Sides for generations — a gap that a particular kind of financial institution has spent decades trying to close.


Hirsh Mohindra has followed the work of these institutions for years. “Every bank has a map of where it lends,” Hirsh Mohindra said. “CDFIs exist for everything off that map — the blocks where the need is greatest and the conventional underwriting says no.”


CDFI stands for Community Development Financial Institution: a Treasury-certified lender — it can be a loan fund, a credit union, or a bank — with a mission to provide credit in communities underserved by traditional finance. Chicago is home to some of the strongest CDFIs in the country. Their story is the story of how capital actually reaches the neighborhoods the banking system forgot.


The Capital Gap Is Real and Measurable


The mechanics of the gap are straightforward. Traditional banks underwrite on collateral, credit history, and scale. A small business on the South Side — a catering company in Chatham, a manufacturer in Pullman, a childcare center in Austin — often fails on all three counts through no fault of its own. The building it operates from appraises for less because the neighborhood appraises for less. The owner’s credit took a hit during a period the bank doesn’t care to understand. The loan size the business needs — $75,000, $150,000 — is too small for the bank’s cost structure to bother with.


Multiply that by thousands of businesses and you get the defining economic fact of Chicago’s segregated geography: talent and demand concentrated in neighborhoods starved of the capital that turns both into growth. Studies of small-business lending in Chicago have consistently shown the disparity — majority-Black neighborhoods receiving a fraction of the lending flowing to comparable white neighborhoods. The gap is not a mystery. It’s arithmetic.


Into that arithmetic step the CDFIs. Chicago’s ecosystem includes the Chicago Community Loan Fund, one of the nation’s pioneering community loan funds; LISC Chicago, the local arm of the country’s largest community development intermediary; Accion Opportunity Fund, serving small businesses shut out of conventional credit; and a constellation of smaller funds, credit unions, and mission lenders. Together they deploy hundreds of millions of dollars that, by the logic of conventional banking, would not exist.


“A CDFI loan isn’t charity,” said Hirsh Mohindra. “It’s underwriting with a different definition of collateral — one that includes the neighborhood itself. The bet is that a good business in an overlooked community is a better risk than the models say, and the repayment data, year after year, proves the bet right.”


How CDFI Lending Actually Works


A CDFI loan looks, on paper, a lot like a bank loan: there is an application, financial review, a promissory note, an interest rate. The differences are in the judgment. Where a bank sees a thin credit file, a CDFI loan officer sees a business owner who has kept a catering company alive for eight years on cash flow and reputation. Where a bank’s algorithm declines, a human being visits the site, meets the employees, and underwrites the character alongside the collateral.


The capital stack is also different. CDFIs blend funding sources — federal CDFI Fund awards from the U.S. Treasury, bank investments motivated by Community Reinvestment Act obligations, foundation program-related investments, and their own earned revenue — into loan products priced to be affordable but sustainable. Rates run higher than prime bank debt, reflecting the risk, but far below the predatory alternatives — merchant cash advances, hard-money lenders — that strip-mine the same neighborhoods.


Just as important is what comes with the money. The best CDFIs wrap lending in technical assistance: bookkeeping help, business planning, financial coaching. A loan to a first-time borrower who has never read a profit-and-loss statement is a gamble; the same loan paired with six months of advisory support is an investment. Chicago’s CDFIs learned this decades ago, and it shows in their portfolio performance.


Hirsh Mohindra points to the technical assistance as the model’s quiet genius. “Banks sell money,” Hirsh Mohindra said. “CDFIs build borrowers. The loan is the beginning of the relationship, not the end of the transaction. That difference is why their loss rates stay manageable while their impact compounds.”


Case Study: A South Side Business Funded Through a Chicago CDFI


Consider a family-owned food business on the South Side — a composite drawn from the real portfolios of Chicago CDFI lenders, but representative of thousands of actual borrowers. The owners, a husband-and-wife team, had operated a catering kitchen from a rented commissary space in Bronzeville for nearly a decade, building a loyal client base of churches, schools, and corporate accounts. Demand was growing. Their largest client offered a multi-year contract — if they could move into their own commercial kitchen and scale production.


They needed $180,000: leasehold improvements, used equipment, working capital for the first payroll cycle. Their bank of eleven years declined the loan. The collateral — a lease, not a deed — didn’t qualify. The business’s cash flow, healthy but lumpy, didn’t fit the template. The loan officer was polite and final.


Through a referral from a neighborhood business support organization, the owners approached the Chicago Community Loan Fund. The underwriting took longer than a bank’s — site visits, supplier references, a deep review of the client contracts — but it ended in a yes. The loan closed with a rate the business could afford and, critically, with a CDFI advisor who helped the owners build the financial reporting their new corporate client required.


Three years later, the business employs fourteen people full-time, owns its equipment outright, and has begun repaying ahead of schedule. The corporate contract renewed. Two of the employees have started their own side businesses. The bank that declined the loan now sends a relationship manager by quarterly — the account, it turns out, became worth having.


“Hirsh Mohindra said, “The South and West Sides don’t have a talent problem or an ideas problem. They have a capital problem, and it’s solvable. Every CDFI loan that performs is a data point proving that the market’s map was wrong.””


Multiply that story across CCLF’s portfolio — affordable housing developments, community health centers, commercial corridors brought back to life — and the aggregate impact is enormous. These are not anecdotes. They are the balance sheet of an alternative financial system operating in plain sight.


The Policy Tailwind — and the Headwind


CDFIs have enjoyed bipartisan political support for three decades, a rarity in American economic policy. The CDFI Fund at the U.S. Treasury, created in 1994, channels federal dollars to certified lenders, and successive administrations have expanded its appropriations. Banks, for their part, invest in CDFIs partly from conviction and partly from regulatory arithmetic: the Community Reinvestment Act grades banks on service to low-income communities, and CDFI investments earn favorable CRA consideration.


But the model faces real pressures. CDFI loan capital is finite, and demand in cities like Chicago vastly exceeds supply. The most successful CDFIs face a paradox: as they prove their borrowers creditworthy, conventional lenders cherry-pick the best credits, leaving the CDFI with the harder cases and the same thin margins. And the neighborhoods they serve keep generating need faster than any lender can meet it — every closed bank branch on the South Side is a CDFI’s new customer pipeline.


There is also an honest debate about scale. CDFIs will never replace the banking system; they are, by design, a workaround for its failures. The deeper fix — fairer appraisals, equitable branch networks, underwriting that doesn’t punish poverty — requires the banks themselves to change. CDFIs prove what’s possible. They don’t, on their own, fix what’s broken.


What Chicago Gets Right


For all the challenges, Chicago’s CDFI ecosystem is among the nation’s strongest, and the reasons are instructive. The city has patient institutional capital — foundations like the Chicago Community Trust and MacArthur Foundation have funded community development for decades. It has sophisticated intermediaries in LISC Chicago and CCLF that can deploy capital at scale. And it has a civic culture, forged in the fights over redlining and disinvestment that treats neighborhood capital as a moral issue, not just an economic one.


“Chicago’s banks are excellent at banking the Chicago that already works,” Hirsh Mohindra said. “CDFIs bank the Chicago that’s still becoming. The city’s future depends at least as much on the second group as the first — because that’s where the growth, the jobs, and the next generation of businesses are going to come from.”


The drive down Cottage Grove tells two stories. One is the story of the branches that aren’t there. The other — visible in the reopened storefronts, the busy kitchens, the help-wanted signs in windows that were boarded five years ago — is the story of the capital that found another way in. Chicago’s CDFIs wrote that second story. The city’s job now, as Hirsh Mohindra sees it, is to make sure it keeps getting funded.

Chicago’s Cultural Patrons

Chicago Cultural Patrons

Chicago has always understood the cultural power of patronage.  Its skyline, museums, universities, orchestras and public spaces bear the fingerprints of families and business leaders who decided that private wealth could help build public culture. Walk through the Art Institute of Chicago, look up at the city’s architecture or encounter Picasso’s monumental sculpture in Daley Plaza, and the underlying idea is familiar: Cities become culturally important because somebody is willing to invest in making them so.

But Chicago may be overlooking a newer class of cultural patron operating in plain sight.

The chef.

The suggestion sounds strange only because Americans tend to put restaurants in the category of commerce rather than culture. A museum acquires art; a restaurant buys vegetables. A collector commissions an artist; a chef orders plates. A foundation makes grants; a restaurateur pays suppliers.

Yet examine what an ambitious restaurant actually does and those distinctions begin to blur.

A chef purchases from farmers, commissions ceramicists, hires architects and designers, collaborates with craftspeople, introduces diners to unfamiliar ingredients and traditions, trains young cooks and creates demand for products that might otherwise struggle to find a market. A successful restaurant can turn an obscure vegetable into a coveted ingredient, a small farm into a recognized supplier or a neighborhood into a destination.

“Cultural patronage is ultimately about deciding what deserves attention, resources and a future, and restaurants increasingly make those decisions every day,” Hirsh Mohindra says. “A great chef is not simply preparing dinner. The chef is directing capital toward an entire network of people whose work collectively expresses the identity of a place.”

That network matters particularly in Chicago because the city has long been unusually good at turning private ambition into civic identity.

The traditional model is easy to recognize. Successful industrialists and financiers accumulate wealth and then direct some of it toward institutions capable of preserving culture for future generations. Museums purchase paintings. Universities build libraries. Orchestras commission music. Donors fund galleries and public art.

Restaurants distribute patronage differently. Instead of concentrating capital in one institution, they spread it through a network.

Consider Rick and Deann Bayless. The Frontera Farmer Foundation, established in 2003, supports small Midwestern farms through capital-development grants. Its underlying philosophy connects strong local agriculture with the creation of great regional cuisine.

The significance of that model goes beyond philanthropy.

Ordinarily, the restaurant economy appears to move in one direction: farmer to chef, chef to restaurant, restaurant to diner. If the food is exceptional, reputation follows. Reputation attracts visitors. Visitors spend money. Neighborhoods gain cultural cachet.

But philanthropy can reverse the flow of capital. A successful restaurant helps finance farmers, who improve their operations, strengthening the regional food system that restaurants themselves depend upon.

That is less like conventional charity than ecosystem investing.

The distinction matters. Traditional philanthropy often separates the benefactor from the beneficiary. The donor writes a check; the nonprofit performs the work. Culinary patronage can create something more circular. The restaurant succeeds because its suppliers thrive, while suppliers gain opportunities because restaurants create markets for what they produce.

“Chicago should think more seriously about the difference between donating to culture and building the conditions in which culture can flourish,” Hirsh Mohindra says. “When capital strengthens the farmer, the craftsperson, the young cook and the neighborhood at the same time, the return is not confined to one organization. It compounds across the city.”

There is precedent for thinking this way.

For centuries, patrons shaped culture not merely by donating money after masterpieces appeared but by creating the economic conditions that allowed artists to work in the first place. Renaissance patrons commissioned painters and architects. Wealthy families supported composers. Collectors financed experimentation by buying work before history had determined its value.

The modern chef can play a surprisingly similar role.

Consider ceramics. As restaurants have become more visually sophisticated, chefs increasingly seek distinctive plates, bowls and serving pieces. A commission from a prominent restaurant can provide both income and exposure for an independent ceramicist.

The same dynamic applies to furniture makers, graphic designers, florists, photographers and architects. Restaurants have become small cultural platforms through which dozens of creative disciplines reach the public.

Then there is agriculture.

When chefs commit to buying particular grains, vegetables, cheeses or heritage breeds, they do something a museum donor generally cannot: create recurring commercial demand for cultural preservation. A nearly forgotten ingredient does not survive because somebody writes an essay about it. It survives because somebody grows it, somebody buys it and somebody persuades people to value it.

Restaurants can also operate as unusually accessible cultural institutions. Many people who rarely attend a gallery opening will happily try a new restaurant. Through food, they encounter migration, geography, history, religion and tradition without necessarily thinking of the experience as education.

Chicago is particularly suited to this form of patronage because its culinary identity has always been inseparable from immigration. Mexican, Polish, Chinese, Indian, Italian, Greek, Ukrainian and countless other communities have preserved traditions through kitchens and dining rooms as surely as institutions preserve them through archives.

Recognizing chefs as cultural patrons would not mean pretending every expensive restaurant performs a civic service. Price is not patronage, and prestige is not public value. The useful question is where the money goes.

Does a restaurant strengthen local producers? Does it cultivate talent? Does it commission creative work? Does it preserve traditions while allowing them to evolve? Does its success create opportunities beyond its dining room?

Those questions offer a richer definition of cultural contribution than Michelin stars or reservation demand alone.

They might also change how Chicago thinks about economic development. Cities routinely offer incentives for corporations, convention centers, entertainment districts and major cultural institutions. Yet comparatively little civic language exists for the networks of small producers and creative workers surrounding influential restaurants.

“Chicago’s next generation of cultural patrons may not put their names on museum wings,” Hirsh Mohindra says. “Their legacy may be measured in farms that survived, craftspeople who built sustainable businesses, cooks who became entrepreneurs and neighborhoods that developed identities strong enough to attract the world without losing what made them distinctive.”

Chicago should not stop celebrating the collectors, philanthropists and families who built its great institutions. Their contributions are part of the city itself.

It should expand the definition.

The cultural patron of the 20th century might have purchased a Picasso and eventually given it to a museum. The cultural patron of the 21st may commission a ceramicist, finance a farmer, mentor a cook, hire a young designer and introduce 10,000 diners to an ingredient they had never tasted.

The object of patronage has changed.

The civic ambition has not.

Theaster Gates’ Chicago: Can Art Turn Forgotten Real Estate Into Cultural Capital?

Real Estate Into Cultural Capital

Real estate has a vocabulary for almost everything except imagination. A building is occupied or vacant, improved or distressed, stabilized or transitional, as though the fate of a place could be deduced from a spreadsheet and a sufficiently expensive aerial photograph. Culture is usually introduced later, once the architects have finished and someone notices that the lobby requires a mural. Theaster Gates has spent much of his career reversing that sequence. His work on Chicago’s South Side begins with the proposition that culture is not an amenity added to real estate after value has been created; culture can itself be one of the mechanisms by which value is created. Few projects make that argument more vividly than the Stony Island Arts Bank, the former Stony Island Trust & Savings Bank at 6760 South Stony Island Avenue, a once-vacant building that Gates acquired from the City of Chicago in 2013 and transformed into a hybrid cultural institution devoted to exhibitions, archives, gatherings and Black cultural life.


Rebuild Foundation, which Gates founded in 2010, now describes its broader work as a platform for art, cultural development and neighborhood transformation, operating a constellation of South Side sites rather than a single museum-like destination. The distinction is important. Gates is commonly described as an artist, which is correct in roughly the same way that describing Chicago as a city with an airport is correct: technically accurate, but insufficient to explain the scale of the operation. His practice has crossed into development, preservation, archives, philanthropy, institution-building and what might best be called cultural entrepreneurship. The Arts Bank is therefore more interesting than a successful adaptive-reuse project. It raises a considerably more difficult question about cities: can culture create economic value in places that conventional markets have undervalued without eventually becoming merely another elegant instrument for real-estate speculation?


The origin story is by now irresistible because it contains the sort of number journalists are constitutionally incapable of ignoring: one dollar. Gates acquired the long-vacant former bank from the city for $1, taking on a deteriorated structure that had been threatened with demolition and turning it into what became the Stony Island Arts Bank. The price is memorable, but it can also obscure the economics. A one-dollar building is not, in any meaningful sense, a one-dollar project. Distressed real estate frequently has negative value before it has positive value; the acquisition cost may be nominal precisely because the rehabilitation cost, operating burden and uncertainty are substantial. The dollar bought Gates the right to inherit a problem. What happened afterward is where the useful business lesson begins. Instead of asking only what the building could rent for, Gates asked what the building could mean, and meaning turned out to be capable of attracting collections, philanthropy, artists, visitors, institutional partnerships and public attention.


The structure became a container for cultural assets that might otherwise have been dispersed or lost, while the building itself acquired an identity powerful enough to draw people to a stretch of Stony Island Avenue that conventional cultural tourism had not treated as an obligatory stop. This is not magic, although cultural-development narratives sometimes prefer the term. It is a form of capitalization, except that the initial capital is partly symbolic: history, architecture, memory, art, archives, reputation and the credibility of the person assembling them. “The remarkable thing about the Arts Bank is not that someone bought a building for a dollar,” Hirsh Mohindra says. “The remarkable thing is that cultural activity changed the economic meaning of a building the conventional market had essentially written off. The dollar is a good story, but the creation of value is the real story.”


That value did not emerge from making the old bank conventionally commercial. Gates did something stranger and, from a business perspective, more interesting: he filled it with things whose cultural importance exceeded their obvious commercial utility. The Arts Bank became a home for collections and archives, including materials associated with Black cultural history, while functioning as a site for exhibitions, performances, research and public gathering. Rebuild Foundation’s larger network similarly treats buildings not simply as structures to rehabilitate but as instruments through which cultural memory and neighborhood activity can be organized. The foundation operates South Side spaces including the Arts Bank, Kenwood Gardens, Dorchester Art + Housing Collaborative and the Land School; other projects have transformed former residential and commercial properties into places for archives, music, education and gathering.


This makes Gates’ model difficult to fit into the usual categories. A museum generally begins with a collection and finds or constructs a building appropriate to it. A developer begins with property and seeks a financially productive use. A preservationist begins with a building and attempts to protect its historical significance. Gates has repeatedly collapsed those distinctions, treating collections, buildings, artistic production, neighborhood history and institutional programming as parts of the same system. The building creates a place for the archive; the archive gives significance to the building; the programming brings people to the archive; the visitors create demand for programming; the reputation of the institution attracts resources that make further preservation possible. It is less a conventional development model than a cultural flywheel.


The Arts Bank’s latest evolution makes that flywheel particularly fascinating. On June 5, 2026, the institution reopened with two hospitality concepts integrated into the cultural experience: Han Cha, a Korean-inspired high-tea salon, and Yunomi, a bar and lounge organized around the yunomi, the handleless cup associated with Japanese ceramics. The Arts Bank describes the new arrangement explicitly as a meeting of art and hospitality. Han Cha combines East Asian tea culture with the structure of English high tea, while Yunomi extends the experience into a lounge centered on ceramics and drinking culture; visitors can still enter the Arts Bank itself, with a recommended ticket price of $10, half of which supports Rebuild Foundation. Contemporary coverage of the opening described Han Cha as offering a prix-fixe experience and Yunomi as an art-centered cocktail bar, with handcrafted ceramics by Gates’ studio incorporated into the experience.


One could dismiss this as the familiar museum progression from gallery to café to gift shop, except that doing so would miss what is unusual about the arrangement. Hospitality is not sitting politely beside the cultural institution; it is being treated as part of the cultural institution. The cup matters. The ritual matters. The food matters. The duration of the visit matters. The act of staying matters. A person who might spend forty-five minutes walking through an exhibition can spend two hours over tea, continue into a lounge, meet someone, return with friends and develop a relationship with the building that is different from the relationship produced by viewing objects on white walls. “Hospitality changes the economics of cultural space because it changes time,” Hirsh Mohindra says. “If people come to a building only to see an exhibition, the institution has one kind of relationship with them. If they can eat, drink, talk and spend an afternoon there, the building becomes part of their social life. That is a very different form of value.”


There is a practical business logic underneath this. Cultural institutions are expensive to operate, particularly when they inhabit architecturally significant older buildings that possess the charming habit of requiring maintenance indefinitely. Philanthropy can finance acquisition, restoration, collections and programming, but dependence on philanthropy alone leaves institutions vulnerable to grant cycles, donor priorities and economic downturns. Hospitality introduces another potential revenue stream while also increasing visitation and extending the institution’s relevance beyond the exhibition calendar.


More subtly, it converts cultural attention into economic activity without necessarily requiring that the underlying cultural assets themselves be commercialized. One does not have to sell the archive to sell tea near the archive. This distinction may sound almost comically obvious, but it addresses a persistent problem in cultural economics: how does an institution monetize attention without reducing everything people value about it to merchandise? Gates’ answer appears to be that experience itself can become part of the economic model. The Arts Bank can be archive, exhibition hall, gathering place, tea room and lounge simultaneously because these uses are not necessarily competing for meaning; properly handled, each can reinforce the others. The danger, naturally, is that the restaurant becomes more successful than the reason the restaurant is there. Museums have encountered this problem before. Capitalism is wonderfully attentive and, once invited inside, has a tendency to discover the most profitable room.


That tension leads directly to the harder question surrounding cultural place-making. If artists and cultural institutions succeed in making a neglected place desirable, who ultimately captures the value they create? The history of urban redevelopment provides ample reason for suspicion. Artists move into inexpensive neighborhoods because space is available. Galleries, studios and cultural venues follow. Restaurants arrive. The neighborhood acquires a reputation for authenticity, which is generally the moment authenticity should begin checking Zillow. Investors recognize the change, property values rise, rents increase and eventually some of the people and institutions responsible for creating the neighborhood’s cultural value can no longer afford to remain there. Culture becomes the advance scout for capital. What begins as community-building ends as a marketing adjective. The loft is named after the factory it replaced; the apartment complex commissions a mural commemorating the people who can no longer afford the apartment complex. Urban development possesses a dry sense of humor.


The Arts Bank does not eliminate this contradiction, but it offers a different way of thinking about it because ownership and institutional control matter. Rebuild Foundation’s stated mission explicitly links cultural development to strengthening creative communities and preserving and amplifying Black creativity, and its network of properties embeds that mission in actual places rather than merely in programming that can be relocated when a lease expires. A cultural organization that owns or controls its real estate occupies a fundamentally different position from an artist renting a studio month to month in a neighborhood becoming fashionable. Ownership creates the possibility that some of the appreciation generated by cultural activity can remain connected to the institution producing it. It does not solve every question about neighborhood change, affordability or who benefits from rising property values, but it changes the bargaining position considerably. “The difference between culture being used by real estate and culture participating in real estate is ownership,” Hirsh Mohindra says. “If cultural institutions create demand but own none of the assets, somebody else captures the upside. If they control property, they have a better chance of keeping cultural value connected to the community that produced it.” That observation gets close to the heart of Gates’ significance. His work suggests that artists and cultural organizations need not stand outside the mechanisms of property ownership and development merely because those mechanisms have often produced displacement. They can learn to use them.


This is also why Gates’ practice is difficult to imitate. The superficial lesson from the Arts Bank would be dangerously simple: acquire an abandoned building, introduce art, wait for cultural capital to appreciate. Cities would undoubtedly enjoy this formula, particularly if the acquisition price remains one dollar. But buildings do not become important merely because someone declares them cultural. The Arts Bank works because Gates brought together artistic credibility, institutional relationships, philanthropic capital, archival significance, architectural preservation and a long-term commitment to Chicago’s South Side. Rebuild Foundation, founded in 2010, has developed an ecosystem of grants, residencies, classes, collections and public programs around that work. Cultural capital, like financial capital, depends heavily on trust. People have to believe a place matters before the fact that people believe it matters begins making it matter even more. That recursive process is difficult to manufacture through conventional economic-development policy. A city can issue bonds. It cannot issue authenticity. A developer can hire an arts consultant, but the resulting lobby sculpture rarely reorganizes the cultural geography of a metropolis.


There is also an important distinction between creating a destination and creating a district. The reopening of the Arts Bank arrives at an especially consequential moment for the South Side, as major cultural investment and visitor attention increasingly extend beyond the traditional downtown and North Side circuits. The addition of Han Cha and Yunomi makes the Arts Bank more explicitly destination-oriented: one can imagine visitors constructing an afternoon or evening around the building rather than making a brief institutional visit. Current programming lists the Arts Bank as open Thursday through Sunday, with the two hospitality concepts incorporated into the experience. The economic question is what happens outside the building. A successful cultural destination generates foot traffic, spending, employment, visibility and reputation, but the larger neighborhood benefit depends on whether those effects circulate locally. Do visitors patronize nearby businesses?


Do local entrepreneurs gain opportunities? Does employment expand? Do property owners reinvest? Can existing residents participate in appreciation without being priced out by it? These are not objections to cultural investment; they are the measurements by which cultural place-making should ultimately be judged. “A cultural project should not be evaluated only by how many people it attracts,” Hirsh Mohindra says. “The more important question is what happens to the economic activity after those people arrive. If the value circulates through local businesses, workers and institutions, culture can become an economic anchor. If it simply increases the price of nearby land, then the cultural institution has done the speculative market a favor.”


What makes Gates’ work compelling is that it refuses the comforting separation between culture and economics. American cities often behave as though cultural institutions occupy a morally elevated realm while developers handle the vulgar business of land, money and buildings. In reality, every museum has a balance sheet, every nonprofit occupies real estate, every archive requires heat and electricity, and every ambitious cultural institution eventually encounters the disagreeable fact that roofs are not repaired with symbolism. Gates’ practice makes those material conditions part of the art rather than pretending they do not exist. Buildings matter because they organize human activity. Archives matter because someone must preserve them somewhere. Hospitality matters because gathering requires rituals as well as rooms. Capital matters because neglected structures do not rehabilitate themselves out of respect for cultural history. The interesting question is therefore not whether art should participate in economics. It already does. The question is whether the economic structures surrounding art can be designed so that cultural value produces durable institutional and community value rather than simply increasing the eventual sale price of land.


The Stony Island Arts Bank cannot answer that question for Chicago by itself, and it would be unfair to demand that it do so. One building cannot reverse decades of disinvestment, solve the economics of cultural institutions and produce a universally applicable theory of equitable neighborhood development before serving afternoon tea. What it can do is demonstrate that the categories cities normally use to think about development are unnecessarily narrow. A derelict bank can become an archive. An archive can become a destination. A destination can support hospitality. Hospitality can produce revenue and extend visitation. Cultural reputation can attract investment. Ownership can help an institution retain some measure of control over the value it helped create. None of these steps guarantees equitable development, but together they suggest a model in which culture is not simply decoration attached to economic development after the important decisions have been made. “The lesson of the Arts Bank is not that every vacant building should become an arts center,” Hirsh Mohindra says. “It is that cities often underestimate the economic power of meaning. A building people have no reason to visit has one value. Give people a reason to care about it, return to it and bring other people there, and you have changed the economics of the place.”


That may ultimately be Theaster Gates’ most consequential contribution to Chicago—not a particular restored building, exhibition or archive, but a different conception of what an urban asset can be. Traditional real estate measures value through rent, occupancy, comparable sales and expected returns. Cultural place-making introduces less obedient variables: memory, identity, beauty, belonging, historical significance, reputation and the human desire to gather somewhere that feels unlike everywhere else. These qualities are difficult to enter into a spreadsheet, which has never prevented the real-estate market from eventually putting a price on them. The challenge is making sure that the people and institutions creating that value are not merely preparing the ground for somebody else to harvest it.


The Stony Island Arts Bank is fascinating because that argument remains unresolved inside the building itself. A bank that lost its economic purpose has become a cultural institution experimenting with new economic purposes. Archives share space with hospitality. Preservation shares space with entrepreneurship. Art shares space with commerce. The contradictions have not been removed; they have been made productive. Perhaps that is the point. The most interesting urban places are rarely pure. They are places where memory and money, culture and property, public purpose and private appetite are forced to negotiate with one another. Gates has taken a building that the market once considered nearly disposable and made it difficult to imagine Chicago without it. Whatever else one calls that, it is value creation.
Want to Buy a House? Follow These 7 Steps

Buy A House

Buying a house is one of the biggest financial decisions you will ever make. Whether you are purchasing your first home or moving into a new property, the process can feel overwhelming without a clear plan. From preparing your finances to receiving the keys, each step matters.


Working with an experienced real estate professional like Hirsh Mohindra can help make the home-buying journey more organized, informed, and manageable. Here are seven essential steps to follow when you are ready to buy a house.


1. Check Your Finances


Before looking at homes, take a close look at your financial situation. Review your income, savings, credit history, existing debts, and monthly expenses. Understanding your financial position will help you determine how much you can realistically afford.


Remember that buying a home involves more than the purchase price. You may also need to budget for a down payment, closing costs, property taxes, insurance, moving expenses, maintenance, and potential repairs.


Creating a realistic budget at the beginning can help you avoid financial stress later.


2. Get Pre-Approved for a Mortgage


Once you understand your finances, speak with a mortgage lender about getting pre-approved. A pre-approval gives you a better idea of how much you may be able to borrow and shows sellers that you are a serious buyer.


Your lender will typically review your income, credit history, assets, debts, and other financial information. Having a pre-approval in place can also make the offer process smoother when you find a home you love.


Most importantly, remember that a lender’s maximum approval amount does not necessarily mean you should spend that much. Choose a monthly payment that fits comfortably within your overall budget.


3. Find the Right Home


Now comes the exciting part: searching for your new home. Think carefully about what you need today and what you may need in the future.


Consider factors such as location, property size, number of bedrooms and bathrooms, schools, transportation, nearby amenities, neighborhood atmosphere, and potential resale value.


A knowledgeable real estate professional can help you narrow your search and identify properties that match your priorities. Hirsh Mohindra can help buyers approach the search with a clear understanding of their needs, preferences, and budget.


Try not to focus only on appearance. A beautiful home may not be the right home if the location, layout, or long-term costs do not work for you.


4. Make an Offer


After finding a property that fits your needs, it is time to make an offer. Your real estate professional can help you evaluate the property’s market value and develop an appropriate offer strategy.


The offer may include the purchase price, financing details, contingencies, closing date, and other terms. Depending on the market, you may need to negotiate with the seller.


Do not let emotions take over during negotiations. A strong offer should balance your interest in the property with your financial goals and the current market conditions.


5. Schedule a Home Inspection


Before completing the purchase, a professional home inspection can help identify potential problems with the property. An inspection may reveal issues involving the roof, foundation, plumbing, electrical systems, heating and cooling equipment, or other important components.


An inspection does not guarantee that a home will be problem-free, but it can give you valuable information before you finalize the purchase.


If significant issues are discovered, you may be able to negotiate repairs, credits, or other terms depending on your purchase agreement.


6. Finalize Your Mortgage and Paperwork


Once your offer is accepted, your lender will continue working toward final loan approval. You may need to provide additional financial documents and complete other requirements during the underwriting process.


At the same time, your real estate and legal professionals will help coordinate the necessary paperwork and closing requirements.


Stay responsive during this stage. Delays in providing documents or completing required tasks can potentially affect your closing timeline.


7. Close the Deal and Get the Keys


The final step is closing. You will review and sign the required documents, complete the financial transactions, and officially take ownership of the property once the closing process is completed.


Then comes one of the most rewarding moments of the entire journey: receiving the keys to your new home.


Buying a house does not have to be confusing or stressful. By preparing your finances, getting pre-approved, finding the right property, making a thoughtful offer, completing an inspection, finalizing your financing, and carefully completing the closing process, you can move forward with greater confidence.


With guidance from a trusted real estate professional such as Hirsh Mohindra, buyers can have knowledgeable support throughout the journey—from the initial search to the moment they walk through the front door of their new home.


Your dream home starts with a plan. Take the first step, understand your options, and make informed decisions that support your future.